Chandler Bolt: $30M Net Worth, an $8M Lake Austin Compound, and Why "Owning Is Financially Dumb"
Selfpublishing.com founder Chandler Bolt is worth just under $30M. He turned down ~$20M for his company, spent $8M on a Lake Austin compound he wouldn't recommend, and carries an $8M whole life policy.
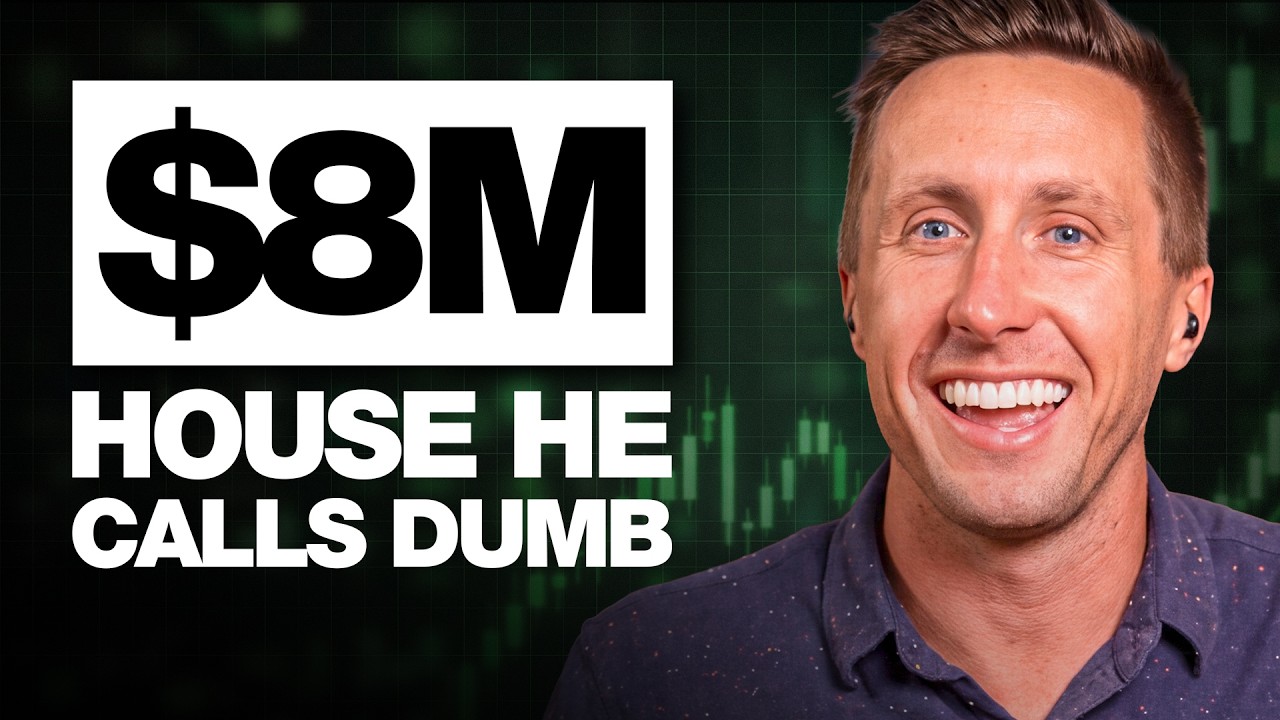
Chandler Bolt grew up in the middle of nowhere, South Carolina, made his first six figures painting houses in college, and dropped out of the College of Charleston at 19 to write a book. That book turned into selfpublishing.com, which has published 7,000 books and done about $81M in sales. Today he's worth just under $30M, turned down roughly $20M for the company, and spent about $8M on a Lake Austin compound he calls "financially dumb" for most people. He'd buy it again anyway.
Like all Moneywise episodes, Chandler breaks down his net worth, income, portfolio, and monthly expenses and then I, your humble host, pick it all apart.
We also went deep on: the six-year math behind turning down $20M, the $6.5M house plus $1.5M renovation and its $5K a month of upkeep, why he has no magic number and watches inflows against outflows instead, the AI equity worth $5M on paper that he can't sell, his $8M whole life policy, and what AI is doing to the book business.
Below you'll find my summary of the episode along with the entire transcript.
And by the way...this podcast, the concept of it came from Hampton. Hampton is a private, highly vetted community for high net worth founders started by Sam Parr. Members range from companies doing 3-5 million in revenue all the way up to hundreds of millions. The reason we started this podcast is because there are amazing conversations about money and growing companies that typically happen only behind closed doors, and we thought it would be awesome to share all of this information. If you're a CEO, founder, or business owner, check this out. New Moneywise episodes come out weekly.
Listen to this episode on:
Now, below are the notes and the full transcript.
The Numbers
- Net worth: just under $30 million on paper.
- Liquidity: about $5M immediately liquid, about $10M liquid within a year.
- The business: selfpublishing.com, 100% owned and bootstrapped. Third-party valuation of about $11M (roughly a third of his net worth). 7,000 books published and about $81M in lifetime sales. Eight figures of revenue a year.
- The offer he turned down: about $20M in 2024, roughly 6x EBITDA.
- The compound: about $8M all in on Lake Austin — $6.5M purchase plus a $1.5M renovation, with about $4.5M on a note and the rest in cash. Around $5K a month in maintenance alone.
- Personal burn: about $50K–60K a month, the highest it's ever been. About half is the house, $5K–10K experiences (one of his two unlimited budgets), ~$5K food, a couple grand on health.
- Giving: about $20K a month, a couple hundred thousand to a few hundred thousand a year to churches and charities (including a school and homes). He counts it before expenses.
- Hard money loans: about $2–5M.
- Whole life insurance: about $900K in cash value on an $8M policy (~$150K a year for five years). "I'm worth more dead than I am alive, apparently."
- Stocks and money market: about $3–5M.
- AI advisor shares: worth about $5M on paper after the company raised $100M at a $1.5B valuation, and not liquid.
- Last year: the business cleared just under $1M of profit, against the "multiple millions" he was used to.
From Painting Houses to 7,000 Books
Chandler grew up in what he calls the middle of nowhere, South Carolina; his parents met working the night shift at a factory. In college he ran a house painting business, knocking on doors around Summerville, and made six figures for the first time. "I'm learning more doing it than I am actually going to college and learning from professors who have never done it." So at 19 he dropped out of the College of Charleston and wrote a book with his brother. It took off, so did the next one, and when people asked how, he turned the answer into what's now selfpublishing.com.
On Daniel's 1-to-10 scale of "I've made it," he puts himself at a four. The goal is to go from eight figures a year to nine by building a media company inside the company, and ultimately "running a billion-dollar company that changes the world."
The Six-Year Math Behind Saying No to $20M
In 2024 he was offered about $20M for the company, around 6x EBITDA, a deal most people would take. Chandler's contrarian read: taking a 6x multiple means betting you can rebuild something this size in six years. "It took me over a decade to get to this point, so I would not bet on that." Because he's bootstrapped, owns 100% of it and the business "just spits off a ton of cash," selling made no sense to him. He admits key-man risk would ding the valuation today.
The $8M Compound: "Financially Dumb," and He'd Do It Again
When he first moved to Austin, Chandler leased Sam Parr's house. Back then he thought renting was lighting money on fire. Now he owns an acre and a half on Lake Austin: a 1,000-square-foot boathouse on the water, a 4,000–5,000-square-foot house on the hill, a pickleball court, pool, sauna, cold plunge and a couple of boats. He bought it for $6.5M, put $1.5M into the renovation, and carries about $4.5M on a note. The idea was a compound where he'll raise his future family, and a home base where "people come to me."
His verdict: "I would, but I would not recommend it." Between roughly $5K a month in maintenance and the cash it ties up, "it's really stupid to own for most people until you get to a certain point. It's financially dumb." If you buy for the feeling, fine, but admit "it's not gonna math." Last year, when profit dropped to just under $1M and outflows came close to inflows, the house turned into "more of a ball and chain" than "this life-giving thing."
No Magic Number: He Watches the Gap
Asked for his threshold number, Chandler says there's no amount that would make him feel done. "Maybe so, but I wouldn't be satisfied" (at $100 billion). Like Alex Hormozi, he says his mood tracks the business's cash flow: "If the outflows are greater than the inflows, that stresses me out." That's why he keeps his personal nut low. For years, his fractional family office introduced him as the guy who "lives on beans and rice in California."
What he does splurge on is experiences, one of his two unlimited budgets: the roughly $10K BMW Ultimate Driving Experience he promised himself as a kid, taking his dad to the national championship to watch Clemson, and finally going to the US Open.
Investments: The Hits, the Misses, and $5M He Can't Touch
"Don't think you're smarter than the experts. You're not." His best investment has always been the core business, including small acquisitions like the selfpublishing.com domain, which he turned into a seven-figure income stream and eventually rebranded the whole company around. A larger multimillion-dollar roll-up was a mistake that "took my eye off the ball." His favorite line on it: most businesses die of indigestion, not starvation.
His verdict on venture: "a horrible asset class, and most people should just avoid it like the plague," with private equity "way better." The cautionary tale is advisor shares in an AI company that later raised $100M at a $1.5B valuation. On paper his stake is worth about $5M, but only seven people got liquid in the secondary (more would have meant a tender offer), and he wasn't one of them. The lesson: write liquidity rights (at least a right of first refusal) into your terms. Today he thinks he might get 40 cents on the dollar in a secondary.
The Case for Whole Life (and a Fractional Family Office)
Chandler is a whole life advocate, done right: "the most important number is the fee." About $150K a year for five years bought a guaranteed death benefit of at least $8M, and he can borrow against the cash value. That's the "infinite banking" pitch. Daniel adds context: level term premiums are fixed only for the term and get repriced after it, unpaid loans reduce the death benefit, and whole life costs far more. MoneyGeek's 2026 average for a healthy 40-year-old buying $500K of coverage was about $59 a month for 20-year term versus $574 for whole life.
For a decade he's worked with a fractional family office (ARC) on the deal "I'm gonna pay you $1 for every $3 that you save me in taxes." His caution is complexity: "fend off complexity at any and every turn." His rule of thumb is that it starts making sense once you clear $500K a year.
AI and the "Messy Middle"
AI is flooding the market with "crappy AI books," but it's also made ghostwriting better and faster for his authors. Internally, AI has added about $1M in revenue over the last year. His hot take: AI has made most of his team 10–30% more productive, "but that's only valuable if you can either cut ten to thirty percent of your staff or drive thirty percent or more revenue. 'Cause if neither one of those are true, well, then you just paid for the privilege of your people having more free time."
Other Key Quotes
"If I sell, well, then I'm basically just saying that I've got six years to build something to this size."
"It's really stupid to own for most people until you get to a certain point. It's financially dumb."
"I would, but I would not recommend it."
"If the outflows are greater than the inflows, that stresses me out."
"I'm worth more dead than I am alive, apparently."
"Most businesses die of indigestion, not starvation."
"You just paid for the privilege of your people having more free time."
Links You Might Like
- Join Hampton Community: https://joinhampton.com
- The Hampton Wealth Report (50+ founders worth $10M–$4B reveal their personal finances): https://joinhampton.com/mw-wr
- Chandler's company: selfpublishing.com
- MoneyWise Podcast: Full episode archive
Full Transcript
Daniel Berk: My guest today is Chandler Bolt, who grew up in what he calls the middle of nowhere South Carolina. His parents met working the night shift at a factory, and in college, Chandler did a house painting business where he would run around South Carolina and knock on doors, paint houses. He ended up making six figures for the first time. Doing that, he was learning more than what he figured he would have been with his professors at college. So at nineteen years old, he dropped out of the College of Charleston and wrote a book, and it took off. So he wrote another book, and it took off too, and people started asking, "How are you doing this?" So he turned that into an entire company called selfpublishing.com. And by his count, it's published seven thousand books and done about eighty-one million dollars in sales. Today, his net worth is just under thirty million dollars, and he's turned down offers as much as twenty million dollars for his business. I asked Chandler what number would let him feel done, and he said there isn't one. He also thinks he's probably already hit it, so this is a really interesting question and a really interesting response. Talking about what that final number is for you and what it needs to be before you can really relax and stop working for the rest of your life, these are the types of things that people talk about in Hampton all the time, and I just get to bring them out into the open with you guys. Hampton is a private network for high-growth founders and CEOs, and on average, they're doing, like, twenty-five million dollars in revenue. If that sounds like your world, you gotta check it out at joinhampton.com. All right, here's what we cover in today's episode. First, the six-year math behind saying no to twenty million dollars. Then we get into the eight million dollar compound that he built in Austin, including the one point five million dollar renovation and the five thousand dollar a month it costs just to maintain. And he'd do it all over again, but he would not recommend it for those who are asking. And we close with an eight million dollar whole life policy and a five million dollar paper stake in AI. Chandler's super open about his numbers in this episode, and he's got a lot of very interesting takes and philosophies on life and on wealth, and so I'm super excited to share this episode with you all. Again, this is Moneywise. I'm Daniel Berk. Here's Chandler. Welcome back to another episode of Moneywise. Thanks, Chandler Bolt, for joining me on the show today. How you doing, man?
Chandler Bolt: Daniel, great to be here.
Daniel Berk: Dude, we, uh, we met officially back in Austin, I don't know, like six, seven months ago now. Uh, you had just done a, a big show or talk on stage for selfpublishing.com, really all about, like, publishing books, which, you know, I won't steal any of your thunder about what your business does, but I feel like we've sort of gotten to know each other a little bit, uh, since then. And I remember distinctly that you and I have a similar story, uh, of Charleston, and so I'd love to understand. I mean, I think your business kind of entrepreneurial journey starts all the way back in the sticks of the low country, if I'm not mistaken. So tell me a little bit about that.
Chandler Bolt: Yeah, well, it's funny, you, you know, you, i-in the Somerville area, that's where I ran my first six-figure painting business, living with my brother, who played in NEEDTOBREATHE at the time. And yeah, that was the early days of entrepreneurship is running a house painting business, knocking on doors, painting houses. It was a wild time.
Daniel Berk: How do you go from that to what you're doing now, which is, like, a, a website to basically empower people to publish their own books? I mean, those are two very different worlds.
Chandler Bolt: Yeah, I mean, my whole background has just been do it, figure it out, and then s- you know, maybe teach it afterwards.
Chandler Bolt: But I, I just learn by doing, and so I was running six-figure companies and, and, you know, in college, that was my first time hitting six figures with my house painting company. And I just realized I'm learning more doing it than I am actually going to college and learning from professors who have never done it. So I dropped out. And so as I was dropping out, I wrote a book about some lessons I'd learned, and I wrote that book with my brother. Uh, and then the book just started taking off, and then did another one, and that book started taking off, and then people started asking how to do it. I'd never heard of this whole online marketing world. That was a very foreign concept to me and, but then I had got a mentor that started teaching me on it, and we started ultimately what's now selfpublishing.com.
Daniel Berk: That's cool. When you think of what you want out of your publishing company and, and some of the, the kind of where you are now and where you're headed, uh, I'm curious to understand really the, the money component, which we talked a little bit about before this episode. But I think what makes you unique to this show is even something you said right before we jumped on, which is that you're, you're trying to start a media company. You have some pretty big, uh, exciting hopes and, and dreams behind this kind of new property under the self-publishing umbrella. So with what you've already done in your journey and in your business building story, where are you at now? If, if ten is, "I made it. Uh, I'm done. I'm retiring. You know, I don't need to ma-make another dollar ever again for as long as I live," if that's the end, where are you at right now in that journey? And let's kind of work backwards from there.
Chandler Bolt: Say probably a four. We're just getting started.
Daniel Berk: A four? Okay.
Chandler Bolt: I mean, there's, we've done a lot of cool things, fun things. Uh, we published seven thousand books. The business has done eighty-one million in sales or so over the lifetime. Uh, made a bunch of money, uh, which I'm sure we'll talk about on this show uniquely, where I don't usually talk about that. But if you're not growing, you're dying, and, and we're just, this is the warm-up phase. And I know kind of it's just funny, we met at New Media Summit, and, you know, I just have realized what got us here won't get us there. We do eight figures a year. That's great, but if we wanna get to nine figures, we're gonna have to start building out the, the media, basically a media company within the company. And so that's what we've been thinking about and, and doing a lot on. And I mean, I think ultimately, just zooming out, my goal and mission, and I know what I'm capable of, is running a billion-dollar company that changes the world, and long after I'm off this earth, it's still here making a positive impact. And so what I'm doing now is a step in that direction, but nowhere near, uh, where we're gonna end up.
Daniel Berk: Yeah, I love that. I think, uh, I resonate with that as well. I don't know what my number out of ten would be. I'd probably be somewhere around a three or four as well. I feel like, uh, my, most of my journey is still ahead of me, which is an exciting place to be, although obviously so much exciting things have already happened. So I'd love to start with, uh, the numbers page. You sent me a bunch of breakdowns ahead of time. That was helpful. But let's just real quick hit run through your own personal numbers, and then let's talk a little bit about, uh, a few of the angles that I think make your story so unique. Um, if you wanna start with paper net worth, what is the paper net worth right now for you personally? And maybe share a little bit about your business as well and how that breaks down.
Chandler Bolt: Yeah. So paper net worth is just a shade under thirty million. Um, that's on paper. Liquid is, immediately liquid would be about five.
Chandler Bolt: Liquid within a year would probably be more in the ten, ten and some change range. And I would say, you know, a third of that net worth is my business, uh, valued at about eleven million bucks. I think that's pretty conservative. That's a third-party valuation. I've been offered almost double that, uh, to buy the company, and I turned it down. Um, but that's got a high-level net worth snapshot.
Daniel Berk: And y-you mentioned you were offered about $20 million in 2024, right? Why did you turn that down?
Chandler Bolt: I got a contrarian thought around selling your business. So any business, if it sells, it's on a multiple of EBITDA, right? You- if your-- normal businesses will probably be three to five x EBITDA. I think at that point, I was maybe offered six x or somewhere in that range, which is, you know, most people would say, "Hey, this is a pretty good deal." But my thought is, if, if I sell... Well, first off, I'm not in retirement phase, obviously, and so we're still-- we got a lot more green grass ahead of us. And so if I sell, well, then I'm basically just saying that I've got six years to build something to this size. That's really what you're saying when you take a multiple of EBITDA, and I think no-nobody looks at that that way, but that's how I looked at it. And I said, "Well, it took me over a decade to get to this point," so I would not bet on that, right? It's like I would, I would not place that bet that I'm gonna get to, you know, whatever that is, uh, the, the $20 million-
Daniel Berk: Yep
Chandler Bolt: ... that they offered. I, I, I wouldn't make that bet because... And not, not only is that the bet that you're making, you're really making a bet that I, I'm gonna get to bigger than what this business would be in six years. And so because I'm bootstrapped-
Daniel Berk: Yep
Chandler Bolt: ... own 100% of the company, all that, I mean, the business just spits off a ton of cash. So I don't know. That doesn't really make sense to me to give up.
Daniel Berk: Well, and it sounds like your current valuation, or revenue rather, is $10, $11 million. I mean, so, you know, with typical EBITDA valuation on a, you know, a post-sale, you're already looking at a, a lot bigger offer if you were to sell it now. Is that right?
Chandler Bolt: Exactly. Yeah, I would, I would say it depends. I mean, I've probably got too much key man risk, so that-- there, there's that. That's gonna ding my valuation a bit, but yeah.
Daniel Berk: Cool. Uh, and then, you know, y- I wanna come back to some of the bad investments and slip-ups that you mentioned, which I think are really interesting. Uh, but before we do that, I'd love to understand your personal burn and nut and kind of what it looks like, where that actual money turns into spend. Um, and so we can break it down either monthly or annually, depending on how you have that on your own balance sheet, but walk me through some of the way that you spend that money.
Chandler Bolt: Yeah, it's definitely the highest it's ever been. I'm kind of someone who likes to keep my burn as low as humanly possible. Right now, it's about 50K a month. Uh, the majority, or I'd say about half of that is my home. So bought my dream home on Lake Austin, uh, and I kinda like that. You just-- I wanted to build the compound where I'll raise my future family, and so that's a big part of it. Then it breaks down to probably five or 10 grand a month is experiences. We can talk about that. I've got kinda two spending categories where I have unlimited budget for, and that's, that's one of them. Then I'd say there's a couple grand a month in health, you know, five grand a month in food and stuff like that. So it works out to be maybe 50, 60 grand, uh, a month on personal burn. Uh, but the, I mean, the first five or 10 years of the business, it was basically nothing. I mean, I've got a fractional family office and, uh, they would always joke when they would introduce me to people. They would say, "This is Chandler.
Chandler Bolt: He lives on beans and rice in California." Uh, 'cause it just-
Daniel Berk: That's funny.
Chandler Bolt: I don't know. I'm somebody who wants to keep that personal nut as low as possible. Uh, and but yeah, that's what it is now.
Daniel Berk: What was your net worth and what was your monthly take home when that mindset shifted? Because, I mean, like how long were you spending? You said it was virtually nothing for so long. When did, when did it click in, in your mind that you're like, "Wait a second. I can, I can actually spend money now. I'm making a good amount of money. I should spend some of this"?
Chandler Bolt: I would say in some ways it hasn't clicked. I hate spending money. Now, don't get me wrong. I love spending money on experiences, so that's like my, my unlimited bucket. So for a long time, I've done that, and I'll never forget when, you know, growing up in the middle of nowhere, South Carolina, I said, "Hey, one day I'm gonna make it. I'm gonna make a bunch of money, and I'm gonna come back here, and I'm gonna do the BMW Ultimate Driving experience." And at the time, that was just like the most crazy thing I could think of. And I said, "I'm gonna bring all my f- like my friends and family." And then one day I realized, you know, that's about 10 grand. And I made way more than that. And so I finally came back and did the BMW Ultimate Driving Experience, and I think I've had multiple times like that in my life, whether it's taking my dad to the national championship. I'm a big Clemson football fan. Whether it's finally going to the US Open, which was on my bucket list for so many years. And so I think there's a bunch of moments, and I think a lot of people who listen to this show will resonate, where you've achieved the milestone way before you mentally think that you have. And then when you actually just break out the math and realized, "Hey, I, you know, th-this is 10 grand to achieve this massive bucket list thing that I've thought about for a really long time," it just starts to change the way that you think about it. So I think it was kind of a slow drip there. And I mean, definitely, like once I started clearing seven figures a year, then it was, "Okay, there's a lot-- we got a lot more wiggle room here."
Daniel Berk: Yeah, I'm, uh, I'm in a similar boat. I just recently bought a Tesla Model Y, and, uh, I've never bought a new car before, uh, mostly on principle. I'm like, uh, I-- the depreciation value is just, it's hard for me to justify. I'm like, "Why would I ever do that?" But, uh, I filed my taxes this year, and I was like, "Wait a second. I could just buy a car," and we needed one. Uh, long story short, we got flooded in Charleston during the, you know, the 133-year storm.
Chandler Bolt: Mm.
Daniel Berk: And so I was like, "All right. I'm just gonna, I'm just gonna do this." It's actually very uncomfortable to do that. It kind of goes against, you know, the, the money philosophy you, at least in my, in my experience I had for, for decades. And I was like, "You know what? I'm just gonna buy this car 'cause I can, and, uh, it's a car I want." And so it's interesting when the tides start to shift, and you have to start to like almost go against what you spent years and maybe decades building a philosophy about. Um, that's interesting. Do you know what your threshold number is? That's something we call on Moneywise, like the number of liquid net worth you'll have to have before you don't ever need another dollar in your life.
Chandler Bolt: A-and, and you're talking about just based purely on expenses? Or are you talking about, uh, what like mentally for me to feel good about it?
Daniel Berk: Let's say both
Chandler Bolt: Mentally, for me to feel good about it, there's no amount, uh, that would be... Yeah, there's no amount that I would just say, "Oh, cool. I'm good now."
Daniel Berk: So what, in, like, $100 billion you wouldn't-
Chandler Bolt: Maybe so, but I wouldn't be satisfied.
Chandler Bolt: I would maybe think like, "Okay, I don't have to work again." But I think I've, I've already been at that phase for so long, where it's like, okay, I technically don't have to work again, and but I do because I love it. But I resonate with, I was listening to the Hormozi episode in prep for this. And I thought it was really interesting how h- he said his, almost just like his attitude wildly varies based on the cash flow of the business.
Daniel Berk: Mm-hmm.
Chandler Bolt: That is so me.
Daniel Berk: Yeah.
Chandler Bolt: It's, it's so toxic, but it's very true, where I just, if the outflows are greater than the inflows, that stresses me out. And I don't feel... I, I, I'm so used to having just the inflows be so much, uh, such a delta between that and the outflows that I just feel a lot more comfortable there. And so it's almost not like-
Daniel Berk: Yeah
Chandler Bolt: ... this magical number. It's more about the cadence of that happening, uh, and, and making sure that the inflows are greater than the outflows by a lot.
Daniel Berk: No, I, I think it's, it's interesting to look at people like Hormozi and, and one, in my, in my opinion, try to understand even what's going through their mind when they say the things that they say, 'cause there's so many quite radical things that he teaches about in his courses and in his books. But, uh, you know, I'd, I'd love to understand some of the way that you put your money where your mouth is, literally, in the way that the investments break down. I think, uh, my understanding is that you're a fairly generous person, and so I know faith contributes quite a bit to the way that you give money. Uh, but when you think of what's left over after the spend that you broke down, I mean, where does some of that money go? How are you investing it? You know, is it in stocks or private equity? Uh, and then like philanthropically, what are you doing that, you know, whether it's because of faith or a tax write-off or some combination of the two, what are you doing with that additional money that you have?
Chandler Bolt: Yeah, so o- on the faith and giving side of things, I mean, for me, that's, that's a big part, and that's the first fruits and tithe and all that stuff. So that's rough. I don't, I don't consider that an expense because in my mind, that's even before the expenses, but that's to the tune of about 20 grand a month, so a couple hundred thousand dollars a year to a few hundred thousand dollars a year. In the giving bucket, churches, charities. We built schools. Gosh, we built a school, built a bunch of homes. Um, bunch of stuff that we were able to do through the business, which I think is capitalism and business is the greatest possible vehicle that exists for good. You get to change the lives of your customers, your employees, and then your future family, and maybe even nonprofits if that's your thing, through the fruit and the, the offshoots of what the business creates. And so there's all that. Then as far as the, the investing, I've g- made a ton of mistakes here, and there's a bunch of things that I can share. I think the first thing I would say is don't think you're smarter than the experts. You're not. What it takes to grow it is different than the skill sets that it takes to earn it.
Daniel Berk: So do you have a wealth manager then?
Chandler Bolt: Yeah. Yeah. We've got s- it's basically a fractional family office, which I, you know, I didn't know that what that was. Most people listening probably do. But that's, uh, you know, it... My, my parents met working night shift at a factory, so a family office was not a thing that was discussed around the dinner table. Uh, but, uh, you know, essentially, they, they help me spend as little as possible on taxes and then, uh, invest, help invest as well.
Daniel Berk: And you mentioned some contrarian takes. I mean, I, I have a list of some of the ones that we had discussed ahead of time.
Daniel Berk: But, uh, I wanna talk with, uh, or talk about the own versus lease first because that's one that's a hot topic. I own my house, uh, and you know, Sam Parr, who owns Hampton, who owns Moneywise, uh, talks about how owning a house is, is probably not the right financial decision because of the money suck. Um, but I think you've made some interesting, unique mistakes here, and I think it would be great to learn from you about what those mistakes were, but also your opinion and, and thoughts on why you would own or lease or, or, you know, rent a house.
Chandler Bolt: It's funny, my opinion's changed on this. So when I first moved to Austin, I actually lived in Sam's house. I don't know if you knew that. Oh.
Daniel Berk: That's hilarious.
Chandler Bolt: But I leased-
Daniel Berk: I didn't know that.
Chandler Bolt: I leased, uh, his house for a little bit.
Daniel Berk: Well, shout out Sam for, uh, letting people couch hop in his home back in the day.
Chandler Bolt: Yeah, I mean, I paid him. I paid him rent. Uh, and then it was when they were, you know, kind of about to move to New York and stuff like that. But I, I think at that phase in my life, I would've said, "Hey, if you're leasing, this is so stupid. You're just l- lighting money on fire, and why would you do that? And when you could be basically putting equity in your home, kind of like a 401(k), you know, pay it down." And so that was my view. Now, I think some of it depends on the economy, and the economy has shifted, and, you know, I ended up buying my dream home. G- I'm glad I did. I, in, in a lot of ways I wouldn't change it, but there's a bunch of stuff they don't put on the flyer. It's, you know, my... I, I probably got $5,000 a month in just maintenance on that house, and not only that, is I've got a bunch of money tied up in that house that could be earning and could be growing. And so then, you know, some of my paper net worth is on or in that house. And so that's where I just think it's really stupid to own for most people until you get to a certain point. It's financially dumb. Now, if it makes you feel better, if you feel c- like th- there's the feelings part of it, cool. Then it's just you can admit that it's not gonna math, but it, it's the decision that you choose to do because it's what you wanna do. But there's something to be said for just leasing, and anytime there's a problem, it's not your problem. And you just call somebody, and they fix it, and that's certainly probably the first decade post-college. That's what I did, just to keep burn as low as possible and to have the least amount of responsibility as possible.
Daniel Berk: How much did you spend on your current house? And is that your o- your only residence, or do you have any real estate as well?
Chandler Bolt: Only residence. I have some other real estate in the, in the investing portfolio, but spent 6.5. Put a million and a half in a renovation, uh, on that property.
Daniel Berk: Okay. And that was... Y-you mentioned earlier a compound. Is it like a big plot of land with one house on it, or did you buy several houses on this plot as, like, a compound for your family?
Chandler Bolt: Yeah. So it's an acre and a half on the lake, on Lake Austin, which is the most expensive real estate that exists in Austin, and it's... there's two structures. There's a 1,000 square foot boathouse right on the water, and then there's maybe 4- or 5,000 square foot house on top of the hill. Uh, there's a pickleball court there. I mean, pickleball court, pool, sauna, cold plunge, the lake, couple boats down there, uh, all that stuff. And so that's kind of the... For me, especially at, at the time I worked from home, now I've... we've got an office and building out the HQ here in Austin, but at the time it was, "I don't wanna ever leave, and I hate, I hate inefficiency and just travel and all this stuff." So I'm like, "Hey, I don't wanna ever leave.
Chandler Bolt: I want people to come to me." And so if I got a pickleball court at my house, well then, people will just come here to play. If we've got the lake, people will come here to surf. And so it's just, like, kind of making that the compound and the HQ. Uh, and then now we've obviously expanded to the office and stuff.
Daniel Berk: That's awesome. Uh, it's a dream of mine to, to do something similar. Uh, you know, I... my, my family is all local with the exception of one of my brothers. He's a professional poker player, so he's in Vegas full time. Uh, but everyone else is here local in Charleston. And, you know, we're about 15 minutes in kind of a triangle geographically, but I've eyed a couple plots of land in, like, Daniel Island, Mount Pleasant. I'm like, you know, someday getting two, three acres and building three or four houses with, like, a little, I don't know, community center or whatever you wanna call it like that. That sounds like the dream to me. Um, and so if I'm hearing you right, you were about 8 million all in. Is that a mortgage, or did you do cash or, you know, half-half? Or break that down for me, what that looked like.
Chandler Bolt: Yeah, about 8 million all in. I've got about four and a half on a note, uh, and then the rest is, you know, is just, just cash that I put into it.
Daniel Berk: Is it worth it, do you think? Like, if you were to do it all over again, was that the right decision? I ask every guest on this show what their net worth is. Most of them have to think about it, and it's not because they're hiding something. It's because their money is in dozens of different places. Two brokerages, a business account, some real estate, a crypto wallet they forgot about, a syndicate, and so much more. But we know that personal finance really is not that simple. Silvia fixes that. Silvia is an AI built for one very specific and important job, managing your money. You connect your bank accounts, your brokerage, your credit cards, your crypto. You add your real estate and whatever else you own, and now it knows your entire financial picture. And you can just ask it questions in plain English like, "Should I refinance?" or, "How do I lower my tax rate?" or, "What's actually risky in my portfolio?" Or you can ask, "What's the smartest way to pass this to my kids?" You could ask ChatGPT those questions, but ChatGPT doesn't know what you own. It also isn't trained on personal finance. Silvia is. In accuracy tests on tax, mortgages, and credit cards, it beat ChatGPT, Claude, Gemini, and Grok. In all three categories, Silvia won. The more complicated your money is, the better Silvia gets. Their data shows people who use Silvia regularly grow their network faster than people who don't, and this is the case at every income level and net worth bracket. Go to silvia.com, connect your accounts, ask it the question you've been avoiding, and start understanding your personal finance more accurately than you ever have.
Chandler Bolt: I would, but I would not recommend it. Like, I wouldn't tell people, "Hey, you should do that," because there's just a massive amount of ca- I mean, think about even just the, the investment value of that cash, much less the burn. And so I'll, I'll say this, Daniel, it... you know, last year was the first year in a long time that we had a dip and less revenue and profit than we've had in a really long time. So I'm used to clearing multiple millions a year, and last year was just under a million. And so it was the first time that, kind of like we were saying, where that outf- like, the outflow and inflow were pretty dang close, and I just realized it really stressed me out, and it was not worth it. And so it was a great reminder for me of why I like to keep that nut so small because it just... it takes your eye off the ball.
Chandler Bolt: Just like, you know, we'll c- I'm sure we'll come back to some of the investments and the acquisitions and the, you know, kind of the failed $10 million net worth plan and all that stuff. But in that same way where I took my eye off the ball of the main thing, well then, the main thing suffers, and then that's what props up everything else. And so that's where I think having that is becomes more of a ball and chain for most people than it does this life-giving thing.
Daniel Berk: You know, my, my house isn't $8 million, um, but I'm already, you know, dealing with the, the reality of owning a home always costs so much more money than the cost and value of the home. And so I'll break it down real quick what, what it looks like just very transparently in my life. We had to spend about $10,000 to cut trees down, just to cut them down. Just, just trees were in the way. They were overflowing on the house. You know, lightning and hurricanes would always kind of make it such that, you know, hey, this could fall through our roof. So we had to chop them down. Well, you can't just chop a tree down because it's massive and 100 years old, so you gotta go pay for permits to get the trees chopped down. And while we did that, it ruined-
Chandler Bolt: Welcome to Charleston
Daniel Berk: It's crazy, and, and it ruined our driveway, so now we have to get a new driveway, and that's expensive, twenty thousand dollars of concrete. And meanwhile, those trees that ruined the concrete were also dropping things on our car that dented our cars. And so it's like one thing after another, after another, and then it's, you know, "Oh, the garage is damaged now," and it's, "Hey, you gotta replace your air conditioning condenser unit because the trees that you didn't cut down fast enough dropped things onto the air condensing." So, uh, I mean, I, I think a lot of people listening to this probably know this and either account for that when they buy a house or don't buy a house for those reasons. I think, again, to Sam Parr's point is like, hey, buying a house is always gonna be unintended consequences or expenses rather. Um, I, I prefer owning my house because I like all the pros that come with it being mine. But man, am I reminded consistently all the things that if I was renting this from a landlord, the landlord would be able to deal with those things, and I wouldn't have to. Um, but it's interesting. I think there's, there's two sides of the coin, and people feel very strongly about their, their own opinions on the matter. Um, I wanna move on to some other expenses and investments. You mentioned, uh, some boat slips, Airbnbs, private equity. Walk me through some of those, uh, things on your balance sheet.
Chandler Bolt: Let's see. I mean, I think early on, I lived in San Francisco, so I did a bunch of angel investments and VC stuff, and so some of that's compounded. Some of that has, is worth a bunch of money on paper, and some of that has just totally flopped. And so I think, uh, um, my kind of stance these days is that venture capital really just sucks. It's a horrible asset class, and most people should just avoid it like the plague. And now I've had s- I've definitely had some wins over there, but I think private equity is way better. Now, I've done some, a bunch of hard money loans, so I've got probably two to five million in, in hard money loans and investments and stuff like that. I've got, it's, I guess it's maybe about nine hundred K in cash value whole life insurance, but eight million dollar policy. So y- you know, depending on how you look at that, I'm worth more dead than I am alive, apparently. But, uh, you know, there, there's that, and then there's, uh, you know, like a bunch of other stuff kind of in that whole portfolio of investments. And then obviously I have the normal stuff, the money market accounts, the stocks, the, all that. That's to the tune of probably three to five million, somewhere in that range.
Daniel Berk: Okay. No, that's helpful.
Daniel Berk: I, I would love to know what of these investments you would count as things you would do again, and that you would, if you were talking to a class of ten entrepreneurs who are maybe, uh, several steps behind you, you say, "Hey, these are, these are the..." And this is not financial or investment advice for anyone listening, but I would love to hear from you which ones you think, yeah, that was a smart decision. And then I would, uh, even more would be interested in which ones you would say, "Hey, I would a hundred percent never do that again. I regret it. It was a terrible decision, and here's why."
Chandler Bolt: The best investments I've ever made is investing in myself and investing in the core business. And so if you have a business that is doing well, keep doubling down on that. Now, I've made some, a lot of good moves within that, like I've made a bunch of acquisitions. I've acquired s- websites, domains, even selfpublishing.com, which is what the company is now. That started as a mini acquisition that we built into a seven-figure-a-year income stream for the main business that we then ultimately rebranded the whole company. Now, I've tried to do bigger, more complicated acquisitions, like multimillion-dollar acquisition, where I bought a few companies and a couple sites and then rolled them up into, uh, the business, and I would say that was a mistake, and it took my eye off the ball 'cause it wasn't core to the business. And so there's a quote that I love that you've probably heard, which is, you know, most businesses by of it, die of indigestion, not starvation. It's from trying to do too many things, not a lack of things to do. And so there's this bundle of things that have done decently well, and I've had s- I've had some hard money loans that have done well. You know, the, I think the whole life is smart. I would recommend that. Uh, the money market stuff is smart. I, I would inve-- I mean, this isn't a pure play investment, but investing in a, a family office I think is really smart because they've saved me hundreds of thousands of dollars, if not millions of dollars in taxes over the years. And so those are all in the good investment bucket. I'll, I'll say one that's in the, in the quasi-medium bucket, and then we can talk about a lot of flops, which I've got some, uh, uh, crazy stories on. But the one that the jury's still out on is really interesting. I told you earlier, I think most venture is a, a total scam and, a- and, or not a scam, but it's just horrible asset class. Horrible.
Daniel Berk: Yeah.
Chandler Bolt: And I think equity is worthless. And this is what's so funny to me, is, you know, people get lured by equity, whether it's employees or, uh, you know, investors, they get lured by that equity. But most businesses, they don't sell. It's, you know, whatever, it's a, it's a, it's a, a percentage over a percentage over a percentage that sells, that sells for what you think it's worth on the time period that you think it'll sell, and then that the money actually goes to the investor and, or, or to the founders. And so I took advisor share. I'll, I'll, I'll, uh, I'll, I'll... I won't mention the name to protect the innocent, but I took advisor shares in an AI company. And I think your dream when, especially when you live in San Francisco, is that you, you'll grow the next unicorn. And so crazy thing happened, years later, that became a unicorn. They raised a hundred million dollars at a one point five billion dollar valuation. And so my on-paper equity was and is now worth five million bucks, maybe more, got diluted a little bit. There was not a liquidation event I, it, like seven people got way... What I found out and what I learned the hard way, which maybe this will save people some money, is that, you know, seven people got liquid in that, in that acquisition. And because if they do any more than that, they have to do a tender offer, and then the tender offer will slow down the raise.
Daniel Berk: Yep.
Chandler Bolt: Yep.
Chandler Bolt: And so I was not one of the seven, you know, founders or employees that got liquid in that event. And so I... And I wasn't smart enough to write it into the covenants of my investment that would say, "Hey, any liquidity event, I'm, I'm first in line, or at least I get, I get a, uh, you know, first right of refusal or at least just a right of refusal." So there's a bunch of things that-
Daniel Berk: Yeah
Chandler Bolt: ... I would do differently now to write into those terms with that equity, 'cause I'm still sitting on that paper equity. And it's an AI company, cool. Uh, and they're, they're doing well, but I mean, ChatGPT came out right after that raise. A bunch of other disruptions came out in that raise. So it's like, okay, could I sell that for 40 cents on the dollar probably now in the secondary? Maybe. Uh, is there still a chance that, you know, I can if, uh, exit for up to five million? Sure, but it's a slim chance. And so is that a good investment? I would say probably not, even though it's worth millions of dollars on paper.
Daniel Berk: Interesting. Yeah, I, um, I've talked to guests who have, you know, hundreds of K-1s and guests who refuse to even become involved in private equity for a lot of the same reasons. Uh, and I, I think it's so interesting how alluring private equity can be when you see the concept, you see the industry, you see the future through the founder or founding team's eyes. And, uh, you know, at the end of the day, you know, 10, 20, $100 million equity before it's public, before there's liquidity is $0. And it's really hard to stomach for someone who's invested so much time in that, you know, private equity. Um, but I, I tend to agree with you. It's like, hey, it's, it's actually not worth anything if there's not a liquidity event. So hopefully, there is someday. Um, I, I would love to circle back to, uh, full term life insurance. A lot of people would say, "Don't do that," but if I heard you correctly, you're telling me that's something you did do and would recommend doing. Tell me why.
Chandler Bolt: Whole... Yeah, so it's whole life, so it's infinite banking.
Daniel Berk: Whole life is what I meant, yeah.
Chandler Bolt: And so that's what... Yeah. Yeah. Yeah. So whole life, it's infinite bank- I mean, it... You gotta, you gotta know that they're writing a good policy because there's a lot of, you know, kind of shysters in that world that the fees eat, fees eat returns, right? Everybody knows that, whether it's in investing, in whole life, anywhere else. Like, the most important number is the fee. And then the second most important number is the actual expected return because f- fees eat returns. And so in whole life, yeah, you gotta make sure that the fee structure is correct. But if done correctly, I mean, it's, it's infinite banking. And so rather than term life, where most people would say, "All right. Well, oh, yeah, it's so cheap," you know, buy term, invest the difference, right? Dave Ramsey would probably say. Uh, but yeah, i- if you're broke. Like, yeah, if you need the money, and, and you' gonna keep it over a long period of time. And then guess what? By the time you're close to dying, they're gonna jack up those rates so high to get... It's like playing a g- it's like a little Mexican standoff. I mean, they're gonna get you to cancel your insurance right before you die, so they don't have to pay out the benefit. Whereas whole life, there's a guaranteed death benefit. And so if, if I only gotta put in 900k and over five years or I, I forget what the number is, I think it was, it was even less than that. I think it was 150k, 150k a year for five years, and then I'm gonna get a, at a minimum of $8 million death benefit that goes to my, my family and all that stuff, well, then that just makes sense to me. And meanwhile, I can borrow from that, and I can take that out and pay interest to myself.
Chandler Bolt: And so I still have ac- that, all that money as liquid while still having a guaranteed death benefit. So I just think it's a smart way to check the insurance bucket while also keeping a bunch of your money liquid.
Daniel Berk: One thing worth clarifying is how term life gets priced. A standard level term policy locks in the same premium for an entire term. New York Life and MetLife both say the price goes up once that term ends. If you keep the policy after that, it gets repriced every year as you age. Whole life, on the other hand, covers you until you die and builds cash value. He calls it infinite banking. That means borrowing against that cash value instead of going to a bank. Any loan you don't pay back comes out of the death benefit. Whole life also costs a lot more. MoneyGeek priced it this year for a healthy 40-year-old man buying $500,000 of coverage. A 20-year term policy averaged about $59 a month, whereas whole life averaged $574. Chandler says he put in about $150,000 a year for five years, and that bought him an $8 million death benefit. Yeah, it's interesting. I, I have a 30-year term, and my philosophy on that was, I have two kids. I have a third one coming soon, uh, which everyone who listens to this every week is probably tired of me saying-
Chandler Bolt: Congrats
Daniel Berk: ... 'cause I've been saying it for, like, two months. Uh, but I promise my wife is pregnant, and the baby will be here soon. Um- I got a 30-year term. It's so funny. Uh, we almost went to the hospital the other night, and I was like, "All right. Here it is." Uh, but, you know, false alarm. We, uh... I literally said to my wife, I was like, "All right. I'm getting a few million dollar 30-year term, and if I die after 30 years from now, I've done something terribly wrong if we still need the money." So it basically is a 30-year clock for me to figure out how to not need the life insurance policy to pay out if I die. Um, some might say that's stupid. Some might say that's fair. Uh, I felt, I felt conservative enough and, and confident enough in my, you know, in my next, now it's like 25 years left, to, like, do something right. But what you're saying Is intriguing. I honestly haven't looked much at, at whole life. Uh, it's, it's interesting though. How does a fractional family office help you think through something like that, and also just your finances in general? I've... I know what a fractional family office is, and to your point, I think a lot of listeners do as well, but I don't know how many of them work with a fractional family office, and so I'm interested from your perspective, as someone who's obviously not trying to sell me, you know, what benefits are there to doing that, and what have you seen as, as like a pro or a con to having worked with one?
Chandler Bolt: Yeah. What I found is that most people don't even know what they are and don't work with them, even if they're rich, which is kind of weird to me. I just kind of stumbled on it early.
Daniel Berk: Well, tell us what it is then. I mean, that would be great. Give us a little definition of how that, how that works for you.
Chandler Bolt: Yeah. So if you're super rich, you have a family office. You've gotta be worth north of $100 million to $1 billion for that to even make sense, and then you hire people in that family office, and you have, you know, maybe two to five people, and that's your family office. Fractional family office is basically the same thing but at a fraction of the cost because they have multiple clients. And the one that I work with, they just go 360 degrees of my life. Uh, and so they, they look at... It's basically like, "How do we do family planning?" So, okay, we're gonna make sure w- your will is dialed in, your health insurance is dialed in, your all that stuff.
Chandler Bolt: Uh, just so there's the risk mitigation, and then there's the, the wealth building, and then there's tax reduction, right? So for me, when I first started working with them, and even p- still to this day, that's the most important bucket for me. It's not about how much you make, it's about how much you keep, right? And so I... the whole premise was, "Hey, I'm gonna pay you $1 for every $3 that you save me in taxes," and I like that. Uh, so they can, you know, they save me a ton of money in taxes. They've done some creative structuring and, you know, we can get into that if we wanna nerd out on that, but it just even like business entity structuring to keep a bunch more of the, the cash and the profit while paying less taxes. Um, so that's been really good, and then they do some, uh, wealth growth and investing and stuff like that. Uh, but I've really enjoyed it, and so shout out to ARC. They're awesome. I'm not, uh, not affiliated with them in any way. Uh, but they're, they're great, and I've worked with them for a decade. I will say the cons of that is complexity. And so that's where I think, v- uh, you know, as your wealth grows, you've gotta be real careful about adding complexity, and so that's the part where I would, you know, uh, kind of push back a lot is like, "Okay, yeah, we're just making this complex structure. How much is this saving us?" Because it's adding time and energy and whatever to do that. And so I think for the most part, we've gotten it right, but there's definitely some times where I'm like, "Hey, look, this just doesn't make..." Like, it's basically just job security at that point, which I think that's where people get, you know, anybody who's made a bunch of money, you know, all right, you start getting into some of these rooms, and the, the incentives start getting warped a little bit. And so that would be, I say, the downside. So I'd say if you go in it and work with one, you just need to just fend off complexity at any and every turn.
Daniel Berk: What do you think someone's... Just say how much money should someone have, whether it's liquid or illiquid, their net worth in general. How much money should someone have before a fractional family office starts to make sense?
Chandler Bolt: What they told me is, "Hey, if you're not clearing a minimum of 500k a year, it doesn't make sense to work with us." And so, you know, if you're less than that, you can probably also AI. I mean, that's like-
Daniel Berk: Yeah. Yeah
Chandler Bolt: ... kind of a big new recent development too where, I mean-
Daniel Berk: Yep. Yep
Chandler Bolt: ... most of these companies are realizing that they gotta become an AI company because... or, or a, a, a lot more technical company because previously it's like you just show up with your numbers, and then you have a consultant on the other end, and that's crazy valuable, and that's where they're adding a ton of value, and then they action the things that make the most sense. Well, now you can get as good, if not in some cases better consultation if you know what you're doing going straight to AI. So I would say south of half a million a year doesn't make sense. North of it, it starts to make sense, and then obviously you've got the upper threshold where, okay, just, you know, just use your own family office kinda thing.
Daniel Berk: Every year when summer ends, you tell yourself it's finally time to start taking health seriously, but work picks up, schedules fill, and your health slips down the priority list again. Does this sound familiar? This, my friends, is why a growing number of Hampton members have been loving Daily Body Coach. It's become an inside secret within the community for getting lean, strong, and healthy without the mental load of having to think about training and nutrition. Daily Body Coach is run by a Hampton member, Anthony Monica, who's also a software founder, and you feel that pedigree come through in this experience.
Daniel Berk: As a customer, you get your own team of trainers, nutritionists, and psychologists who take the time to understand how you operate, what tends to throw you off, and what your daily life actually looks like. The result is a highly personalized operating system that's guaranteed to deliver results. If you want to avoid falling off, restarting, and repeating the same old cycle, you need a system that can work long-term, which means it needs to be designed around your existing habits. That's what Daily Body Coach builds for you. So if you wanna transform the way you look and feel and start taking your health seriously over the long term, you gotta try Daily Body Coach. Click the link in the description or go to dailybodycoach.com/moneywise, and I'll connect you directly with Anthony. Yeah, totally. A- um, you mentioned AI, which is a perfect segue. I wanna bring the plane in for a landing, uh, and nerd out for a little bit. Obviously, you know a lot about books because of the company that you run, and I'd love to understand, like, how are you seeing the macro of AI and AI use and AI authorship and AI book publishing, all that? How is that affecting your business, and then how are you, I imagine, proactively creating a moat to solve for that? And obviously, this is, like, not really money related, but you're an interesting guest with an interesting opinion, I imagine, on this topic. So I'm like, "Hey, let's, let's go there. Let's ask. Let's nerd out a little bit on books."
Chandler Bolt: It's changing everything. I mean, I would say there's, there's the business, and then there's the business of what we do. And so just starting kind of the business of what we do, helping people write and publish books, it's flooding the market with a bunch of crappy AI books, which means it's just supply and demand, right? It's just watering down things. But it's also making it easier for people to get their ideas out. And so we're innovating in a wa- in a lotta ways that can help our authors be exponentially more successful. So ghostwriting has never been easier if you know how to do it right, a- and that's where a bunch of people will just click, click a couple buttons with AI and try... think they can ghostwrite a crappy book. Just doesn't work that way. And so we've been able to, you know, f- write way better books for our authors that's in their voice and shortcut the process and leads to massive outcomes in their business. Everything, I mean, where it's, there's a lot of stuff that's still in flux. But it's making everything better for our authors, and so we're able to just better serve people. And so that's the business of what we do. Then there's the actual business, which, I mean, we are just innovating like crazy. We've built entire internal training hubs that train up and review and give feedback on every single call that happens in the business. It's... There's agentic stuff where, you know... I just dropped a video recently on my YouTube channel about we've done about a million in revenue over the last year for the business, uh, just from AI stuff. And so there's a bunch of different levers that I can say, "Oh, that's six figures a year, that's six figures a year, that's six fig-..." of pillars that we've built with AI, so that's really cool. But then I'd say, like probably most business owners, we're stuck in the messy middle too, where, you know, at the end of the day, the whole premise is this is going to lead to higher margin and higher profit by driving more revenue and cutting costs. But I think we're, we're stuck in the middle just like a lot of business owners are that, okay, we've used it to make almost everyone on the team ten to thirty percent more, uh, productive, but that's only valuable if you can either cut ten to thirty percent of your staff or drive thirty percent or more revenue. 'Cause if neither one of those are true, well, then you just paid for the privilege of your people having more free time.
Daniel Berk: Right?
Daniel Berk: Oof.
Chandler Bolt: Or maybe, maybe not even free time, but, like, none-
Daniel Berk: That's gonna be a clip.
Chandler Bolt: So then-
Daniel Berk: I'm putting that on, I'm putting that on Instagram. Yeah, that's, that's good. Uh, that's a hot take.
Chandler Bolt: But, because it's like, hey-
Daniel Berk: And that might offend a lot of people.
Chandler Bolt: But it's the truth. I mean, 'cause look at your AI bill, and it's probably five to ten grand a month if you're running a sizable company. It might be even way more than that. And so then if you are not disproportionately offsetting that with revenue or team reduction, well, then that's not, that's not good spend. Like, that's not a good use of those funds. And so... But, but it's not gonna happen overnight, and so that's where I think us, like many other companies, are stuck in that messy middle where it's like, hold on, this is actually making us less profitable right now in a lot of ways. I know that it will six months from now, twelve months from now, probably pretty radically improve our margins, and we just gotta stay the course, uh, to, to get on the other side.
Daniel Berk: Uh, last question. Same discussion about books. I have two kids. Uh, they love reading books. They're almost five year old and a, a two-and-a-half-year-old. And so we read books every single night. I mean, they're obsessed with it to the point where, like, if my youngest, my youngest will, like, wake up and just, like, jump out of his bed and just, like, come into our bed periodically. Not great, but whatever. He's not old enough for me to get super mad yet. Uh, and he'll bring me a book. And so I'm like, what am I gonna do? Not read this book to my two-and-a-half-year-old? So, you know, he hops up, he snuggles with me, and I read him a book. That's so precious to me, and I think is such a valuable, like, tenet in a child's life. And I have a lot of opinions on this that we don't necessarily have to unpack right now on, like, the value of reading and, um, what happens to a child's brain when they, you know, get transported to another world through a book. Like, how is this generation, uh, let's say, like, currently, like, five to fifteen-year-olds who I imagine are not reading the same way that you and I did when we were kids. How do you imagine the world transforming, for better or worse, with books being more of, like, an optional thing now compared to when we were kids? I mean, that's just how we digested information. I mean, especially pre-internet, there was no other choice. How does the world shift to compensate?
Chandler Bolt: Books have been dead for so long. Books have died so many... I mean, the e-book came out, and it was like, "Oh, print books are totally screwed." And then, uh, so I think this is just the latest iteration of books dying, when in reality, if you wanna stand out, and it's not, let's just face it, it's not that hard to stand out anymore in an AI world as, as everything is so vanilla. I think it's actually easier to stand out as a person, and it's easier to stand out as an author 'cause when you create something that's high value and that's authentic, it stands out. And the smartest, most successful people read. So if you're trying, as a business owner, if you're trying to reach those people, well, then the, the best, most lucrative way to do that is in the form of a book. If, as a, as a parent, if you're trying to reach your kids, well, guess what? AI now makes the ability for you, Daniel, to create a custom children's book for your kid that you can then get printed and that can teach very specific lessons and be fun, and maybe it's their Christmas present where they're the main character-
Daniel Berk: Yeah
Chandler Bolt: ... in the book, right? And so that's what I think-
Daniel Berk: Yeah
Chandler Bolt: ... is really kinda cool in, in that specific scenario.
Chandler Bolt: Now, we've got a whole children's book school arm of the company, and we're seeing a lot of really fun and interesting things there. That's where I think people are gonna keep reading. Now, w- we are seeing a massive trend towards audio. So audiobooks are a, a big portion of book sales, uh, but even still, like, book sales are g- continue to go up, and I think, you know, people are gonna keep reading.
Daniel Berk: Yeah. Yeah, I, uh, I'm a long distance runner, and so audiobooks are how I digest most of the time now because I'm like, what else am I gonna do when I'm running for two, three hours? But I think the, the idea of, like, custom children's storybooks is something I, I'm, I'm... My friend actually launched a product recently. It's called storybookstudio.io, and it's literally that. It's the ability to create a custom storybook of your kids kind of being the main character in their story. And so I, I'm sure there's other products out there like this. Um, I don't know if self-publishing does something like that as well. But I think that's, that is how I believe we'll lean into the next generation is show them that they're in the story. That's a really cool thought. I'm a little scared sometimes. Even the way that I use technology, I'm like, "God, am, am I getting dumber?" Like, I think honestly I am. Sometimes I'm like, I'm actually getting more dumb just because of how much I'm consuming that is not helpful or useful knowledge. Um, so I think there's a balance. It's like we, we gotta figure out how to balance the ability to consume at the pace that we can in twenty twenty-six with what the pace of consumption looked like twenty, thirty years ago. That-- It's like you, you could waste time. People wasted time reading newspapers, read books that maybe were not helpful or useful, but I feel like the speed and rate of consumption has created a, a bit of a predicament for humanity. So I'm interested to see how that develops and how books can play a, a major role in keeping that kind of a straight path.
Chandler Bolt: Yeah. I mean, when everything's on demand, you don't... And now it's thinking for you, it's acting for you, and all this. I mean, there's a lot of beautiful things in that, don't get me wrong. I'm a early adopter and a raving fan. But yeah, it does, it does make you dumb in some ways. Uh, and yeah, we'll, we'll see how it, we'll see how it plays out.
Daniel Berk: Yeah, I'm excited, man. I, I've been following you for a while, and I'll continue to do so. I appreciate you, Chandler. Thanks for joining Moneywise. Again, he's, he's, uh, got a website. It's selfpublishing.com. Check him out if that's something that interests you. But Chandler, man, you're the man. By-- I am inspired to, uh, to take a little bit of a similar route with the compound that you bought. I think that's so cool. Um, I, I have so many questions. I feel like we could probably have a whole episode on just that, so maybe I'll bring you back. Uh, we can do that, 'cause I think there's just so much to unpack there. Uh, but thanks for joining, man. Thanks for your transparency and for opening up your life to us. Uh, and I just appreciate you joining Moneywise today.
Chandler Bolt: You got me to talk about a bunch of stuff that I never talk about. And so thanks, uh, for bringing me on. And honestly, even just the prep for this episode was kinda fun, 'cause it got me to... I don't look at these numbers that often, and I had to really do my homework, uh, to make sure that I was coming prepared. So thanks for having me.
Daniel Berk: Yes. Uh, well, that is always the goal. Uh, so I appreciate you saying that. Thanks again, man. We'll see you next time. What stuck with me the most is what actually stresses him out. He told me there's no magic number for him. What he watches is money coming in against money going out, which sounds super simple, but for years, the gap was huge.
Daniel Berk: And last year, it got super close, and he said it really stressed him out, which I can imagine. It would stress me out, too. That's why he keeps his burn low. He watches the gap. I'm thirty-three. I've got two boys and a third boy on the way, and I'm nowhere near Chandler's number yet. I have a thirty-year term policy and about twenty-five years left on it. I told my wife that if we still need that payout in thirty years, I've done something terribly wrong. I've never priced whole life before this conversation, and so this week, I'm gonna put a whole life quote next to our term policy and then decide with actual numbers what makes the most sense. Spoiler, I probably won't get whole life, but maybe. I don't know. Chandler may have convinced me to actually check it out. Chandler called owning the house financially dumb for most people, but he'd still buy it again. Whether a dream house is worth the cash it ties up comes up in Hampton a ton. Hampton's a private network for high-growth founders and CEOs, and if you're building something real and asking these questions too, go to joinhampton.com. Those are your people. I think something like this comes up in the show quite a bit. You-- People do something that they think was right at the time. They buy something very expensive with their money, and they say, even in hindsight, it was a financially dumb decision, or they would tell other people it's a financially dumb decision. But then right in that same sentence, they said they'd do it all over again. I think that's at the heart of what people do when they have a lot of money. Sometimes they do something that their logical side of the brain says, "This is a stupid financial decision, but I'm gonna do it anyway." And I think that's the cool thing about having money that you can spend however you want, is you can do things that maybe are financially dumb to some other people. Again, that's Moneywise. This was Chandler Bolt. Thanks so much for joining and listening. If you love the episode, please go ahead and subscribe. That helps me out a lot. It is literally how I get paid. It is what puts food on my family's table. This is Moneywise. I'm Daniel Berk, and I'll see y'all next week.

Personally, I find being the CEO of a startup to be downright exhilarating. But, as I'm sure you well know, it can also be a bit lonely and stressful at times, too.
Because, let's be honest, if you're the kind of person with the guts to actually launch and run a startup, then you can bet everyone will always be asking you a thousand questions, expecting you to have all the right answers -- all the time.
And that's okay! Navigating this kind of pressure is the job.
But what about all the difficult questions that you have as you reach each new level of growth and success? For tax questions, you have an accountant. For legal, your attorney. And for tech. your dev team.
This is where Hampton comes in.
Hampton's a private and highly vetted network for high-growth founders and CEOs.