Adam Katz: The Wealth Advisor Worth $35M Who Spends $1M a Year ($300K on Vacations, $35K on Tips)
His dad died with $133K. Wealth advisor Adam Katz is worth about $35M, spends his entire $1M after-tax income every year, and breaks down $300K of vacations, $150K of donations, $35K of tips and the mortgage move most of his clients use.
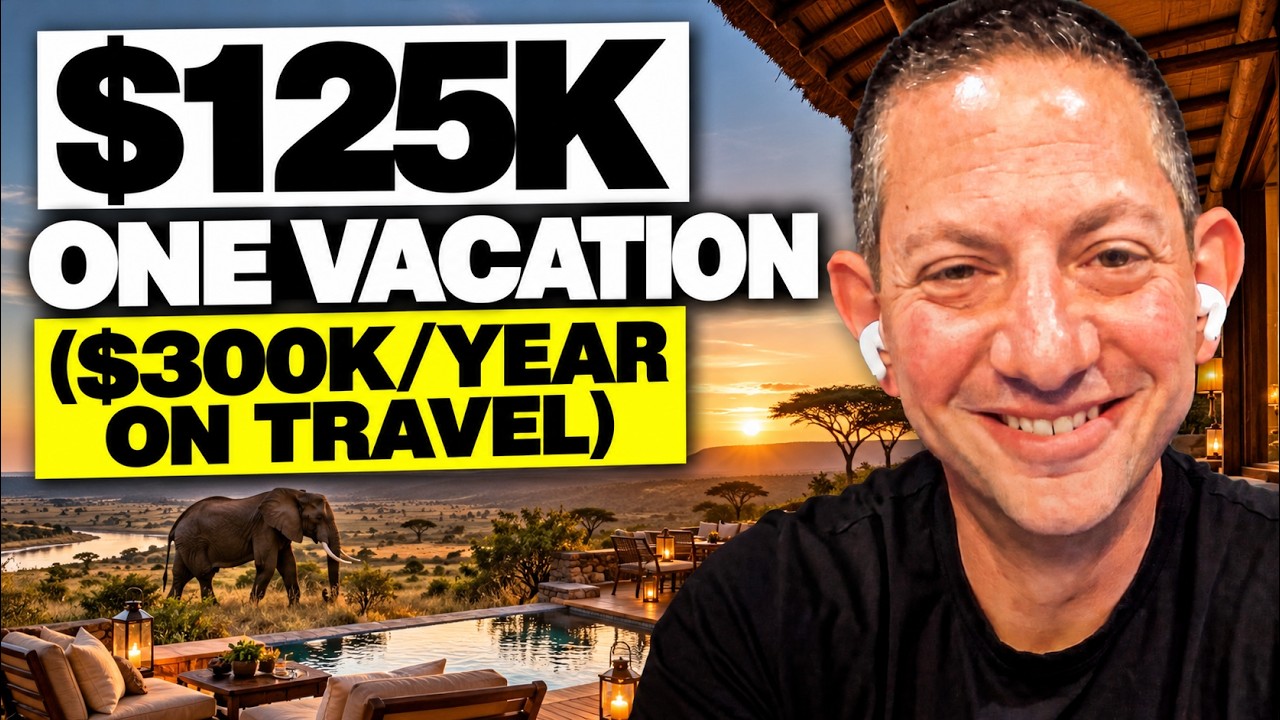
Adam Katz's dad was a guidance counselor in the Bronx who made $48,000 after 31 years and died with $133,000. Adam didn't board a plane until he was 16. He cold-called his way into Merrill Lynch, built and sold a multifamily office, and today advises venture-backed founders while being about as wealthy as they are: roughly $35 million. When he asked his kids to guess the number, one said $8 million and the other said $75 million. He spends his entire $1M after-tax income every year, about $300K of it on vacations and $35K on tips.
Like all Moneywise episodes, Adam breaks down his net worth, income, portfolio, and monthly expenses and then I, your humble host, pick it all apart.
We also went deep on: where the money sits (75% illiquid, 20% cash, 30 K-1s), the buy-with-cash-then-mortgage move for deducting all the interest, how he picks private credit, the three-digit rule, his day-part tipping system and the $2,000 tip on a $3,000 bill, the $33K mattress and $200K watch, and his $20–25M threshold number.
Below you'll find my summary of the episode along with the entire transcript.
And by the way...this podcast, the concept of it came from Hampton. Hampton is a private, highly vetted community for high net worth founders started by Sam Parr. Members range from companies doing 3-5 million in revenue all the way up to hundreds of millions. The reason we started this podcast is because there are amazing conversations about money and growing companies that typically happen only behind closed doors, and we thought it would be awesome to share all of this information. If you're a CEO, founder, or business owner, check this out. New Moneywise episodes come out weekly.
Listen to this episode on:
Now, below are the notes and the full transcript.
The Numbers
- Net worth: about $35 million. He put it at "between 25 and 50" and Daniel called it at 35. He could make all of it liquid in 12–16 months.
- Balance sheet: about 75% illiquid / 25% liquid. Roughly 60–65% in public equities and equity-like private equity, ~10% private credit, ~10% in venture/PE drawdown funds (2018–19 vintages onward), and ~20% in cash earning 3.8%. 30 K-1s every tax season.
- Income: about $1M a year after taxes, and he spends all of it.
- Main house: bought for $3.25M in cash, then took a $2M interest-only mortgage at ~5% (~$100K–105K of interest a year), offset with $1M of private credit paying 10% so the interest is fully deductible.
- Lake house: owned almost a decade, bought 100% with debt (a HELOC plus a mortgage). Interest on both houses: $115K–130K a year. Property tax: $75K–80K.
- Vacations: $250K–300K a year across 6–8 trips, the whole family in first class. Most expensive: a $125K South African safari.
- Restaurants: $100K so far this year, $35K of it tips. Minimums: $10 coffee, $25 breakfast, $25 per bar drink, $50 lunch, $100 dinner. Biggest: a $2,000 tip on a $3,000 bill.
- Donations: about $150K a year, $400K–500K over the last few years, including a full interior renovation of his synagogue.
- Shopping: about $100K in a normal year, $400K–500K this year (watches, bags, two 50th birthdays — the celebrations alone were $100K+).
- The big buys: a $33K Vispring mattress, a $35K Rolex, a Vacheron Constantin tourbillon for over $200K, and a $168K Alpina B8.
- Liability insurance: $45K a year (two houses, four cars, a young driver).
- Threshold number: $20–25M, enough to throw off about $1M a year, or $50–60K a month of spending.
A Guidance Counselor's Son From the Bronx
Adam's dad was a guidance counselor in the Bronx for 31 years and topped out at $48,000. When he sold the family home there was $650,000 on the for-sale sign and only $50,000 of equity left; his parents had used it as a piggy bank for college, bar and bat mitzvahs and weddings. He died with $133,000 to his name.
"I used to think luxury for an automobile was a headrest in the back and a fold-down armrest." Adam didn't board a plane until he was 16, and his feet didn't touch sand until he was 24, at a Club Med in Turks and Caicos where he met his wife, Dana.
Cold-Calling Into Merrill Lynch
In college he heard about a friend making $50,000 in investment banking at Merrill Lynch, more than his dad had made after three decades. So he cold-called his way through the white pages into an unpaid internship, commuting an hour and a half each way for two hours of work. His first job paid $33,000, in wealth management, not banking.
He rose to head of sales and business development at the private bank, joined one of the advisor teams he'd recruited, and eight years later left with them to start a multifamily office. They sold it to what he calls arguably the largest non-bank wealth manager for ultra-high-net-worth clients in the world. That sale, not advisory fees, is why a wealth advisor is as rich as his clients.
Raising Kids in a Zillow World
"Your kids know everything about what you spend," Adam says. "But it's a numerator absent a denominator." After the $125K safari he asked his kids, then 16 to 20, to guess the family's net worth. His daughter said $8 million. His son said $75 million. He and Dana still haven't told them the real number, but for Moneywise he narrowed it to between $25M and $50M. Daniel called it at $35M.
The Mortgage Move: Buy With Cash, Borrow After
Most people can deduct interest only on the first $750,000 of a mortgage. Adam (and, he says, most of his clients) buys the house with cash, takes the mortgage afterwards, and traces the loan to other investments so the interest becomes investment interest. His example: a $3.25M house, a $2M mortgage at about 5%, so $100,000 of interest. Put $1M of that into private credit paying 10% and the $100,000 of income is fully offset. "Not giving tax advice," he adds. Make sure the accountant doing your return understands it.
His private credit is boring on purpose: asset-backed, first-lien loans at about 50% loan-to-value. "You're either going to get paid on time or over time." If a $10M project's borrower defaults on his $5M loan, "even if I have to sell it at a 30 cent discount at 7 million bucks, I just made 40% on the 5 million." He matches the lockup to his own horizon so nobody else's redemptions affect him.
And the 20% in cash? He's paid 3.8% to wait. Swapping millions of accessible liquidity for 4–5% more before taxes, after the mortgage interest is already offset, isn't interesting to him.
The Three-Digit Rule
Ask someone with eight- or nine-figure wealth their net worth and almost nobody can tell you more than the first three digits. Most can't get two. Adam's rule: the money in the digits you can't see doesn't change your life where it sits, but it can matter a lot somewhere else.
A first-class upgrade for the family costs $10K–30K, which is invisible on the balance sheet, but put it against the vacation budget and you arrive rested and with time together. The $33K mattress Dana first slept on in Paris goes against the sleep budget instead. His image is a droplet of water: invisible in a pool, a bathtub, a glass, even a thimble, "then you get it into a baby teaspoon and you finally can."
$35K in Tips: The Day-Part System
At a celebratory dinner with his 12-year-old daughter, the bill came to about $250. A 20% tip felt wrong: it wasn't the waiter's fault they'd drawn a dad and a kid at a four-top instead of a big night out with a $1,000 bill. He left $200. That turned into a system: he tips by meal, not by percentage, and carries only 20s and 100s so he never has to think about it. The bellhop and valet get $20 minimum. Anyone who delivers something to his house gets $100, so the three guys who brought the mattress (and hauled away another one) got $100 each for 22 minutes.
"If I don't know what I have in my pocket, I don't have the right to keep it there." For his 50th he took 14 people to the local steakhouse he and Dana go to almost every week, where the staff always gets $250. The bill was $3,000 and he tipped $2,000, "just to make it a round number." At a $37,000 all-inclusive in Mexico he started tipping $250 a day: $1,500 more for the week, and he never fought for a pool chair again.
Watches, a Green Alpina, and the Bell Curve of Consumption
Adam wore an Apple Watch for 13 years. Then Tourneau wouldn't sell him a $35K matte black Rolex that was "for exhibition only," and Dana spent nine months working a relationship at the local mall until one came in. He has since bought three more nice watches and a green Vacheron Constantin tourbillon, quoted at $191K, that cost over $200K and that Dana calls his "house watch." It's a balance-sheet shift, he says: "you're getting 80, 90 cents on the dollar. You're not getting 30 cents on the dollar." The car to match is a $168K Alpina B8 in Alpina green.
The reasoning is his "bell curve of consumption": spend hard in your 40s, 50s and 60s, because "70s, 80s, and 90s are not guaranteed, and they're not guaranteed healthy." Would you rather die with $800M, or $600M after a lifetime of giving and memory-making? "I don't meet anyone that actually cares."
The Threshold Number: $20–25M
Adam passed his own threshold in a single day, when he sold the firm. His answer as a practitioner is $20–25 million: enough to predictably throw off about $1M a year and spend $50K–60K a month, "probably way wealthier than the wealthiest person you thought existed in your hometown." He also points out that a founder at that level can earn a few hundred thousand a year advising, and that $300K of income would otherwise take another $5–6M of capital to replace.
His legacy plan is fully built (he did it himself) and the goal with his kids is "supportive, not overly enabling." He and Dana once lived in a roach-infested apartment, and he doesn't think his kids need to repeat that. 100% of the profit from his book, Making the Zeros Count, goes to charity.
Other Key Quotes
"I used to think luxury for an automobile was a headrest in the back and a fold-down armrest."
"You're either going to get paid on time or over time."
"If I don't know what I have in my pocket, I don't have the right to keep it there."
"The idea of tipping $250 is mind-boggling to people. But if I bundle it and put it over the $37,000 denominator, it's irrelevant."
"70s, 80s, and 90s are not guaranteed, and they're not guaranteed healthy."
"When you get to like twenty to twenty-five million dollars, you're probably way wealthier than the wealthiest person you thought existed in your hometown."
"I wanna be supportive, not overly enabling."
Links You Might Like
- Join Hampton Community: https://joinhampton.com
- The Hampton Wealth Report (50+ founders worth $10M–$4B reveal their personal finances): https://joinhampton.com/mw-wr
- Adam's book: Making the Zeros Count
- MoneyWise Podcast: Full episode archive
Full Transcript
Daniel Berk: Today's Moneywise guest is Adam Katz. His dad was a guidance counselor in the Bronx and died with only $133,000 to his name. Adam didn't even get on a plane until he was 16 years old, but now he's a wealth advisor and he's as rich as the people that he advises. A few months ago he asked his kids to guess what his net worth was. One of the kids said $8 million and the other kid said $75 million. In this episode we're gonna find out which one of those numbers was closer and we're gonna get into some serious spending details. He walks me through every dollar he spends in a year, the mortgage move he and most of his clients use, why he optimizes life for vacations and how much money he spends annually on those vacations, and a specific tipping system he's created where he always tips way, way more than the average as a point of pride. Adam's entire philosophy of money and wealth revolve around optimizing for moments of outsized generosity. You'll see what I mean after you listen to this episode. Real quick favor before we start, subscribing to Moneywise costs you nothing. It's free to do and means a world of difference to me. If you enjoy this show, please go ahead and hit subscribe. This is how I get paid. I get to talk to founders like Adam inside of Hampton. It's a private network for high growth founders who are doing on average $25 million a year. If that is you, check it out at joinhampton.com. Now let's get into the show. I'm Daniel Berk. Here is Adam Katz on Moneywise. Well Adam, thanks so much today for joining Moneywise. I'm really excited to learn about you, learn what you do, learn kind of what qualifies you to be here on this show. But if we can start with, uh, what you do. Tell me about yourself and what is it that you actually do and how do you work with wealthy people?
Adam Katz: Being on a chat like this, being able to talk about various things around relationships, how it interplays as it relates to money, as it relates to the way we think about parenting and time and health, I feel really, really well equipped to help with that. The nice thing is I have this duality as a peer, as a person who sold the company, went through what I like to call step function wealth creation events, but also as a provider. And to be a s- person that has worked around entrepreneurs and founders for so long, um, and to be able to co-pilot this journey with them has been amazing. So you know, really been doing that for a couple of decades around mostly venture-backed founders.
Daniel Berk: That's cool. When we talked ahead of the show you had mentioned growing up with scarcity and I wanna understand how, how did you go from scarcity in your early childhood to what you are now, which is personally wealthy and then also working with wealthy people?
Adam Katz: Yeah, I tell everyone I used to think luxury for an automobile was a headrest in the back and a fold-down armrest. Uh, my dad was a guidance counselor in the Bronx, was very proud of what he did. Uh, I joke that his mother said, "Irwin, you can go to NYU School of Commerce," which is the business school, the law school or the school of education. She said, "Irwin, they're gonna always want teachers." So he was a guidance counselor for thirty-one years and then an educator for thirteen and there was no excess cash flow in our family. So I didn't really grow up with the idea of what money meant. When he sold his house after my mom died there was about $650,000 on the for sale sign and there was $50,000 of equity. He had used-
Daniel Berk: Wow
Adam Katz: ... the home as a piggy bank forever to get us to go to colleges in a way that felt in line with their values, to pay for bar and bat mitzvahs and weddings, um, and my dad died with $133,000 to his name. So the idea of abundance was always there for love and nurturing, but the scarcity dynamic that most people would have had with money never really crept into our life.
Adam Katz: There was no abundance but I never felt like there was scarcity.
Daniel Berk: Interesting. And did that, or I guess I'm sure it did, how did that affect the way that you grew up thinking about the dollar?
Adam Katz: Yeah, it's a great question and I think in some ways there's so much more subconscious that happened than, than is conscious in that where I landed today I didn't even think was possible. You know, I, I often say that I thought the proverbial doctor lawyer money was wealthy. That was really what my town probably had most of. Um, the idea of having tens of millions of dollars or hundreds I, I don't think that I even realized that was possible. You know, it was an era where the internet wasn't a thing, there was no social media. You didn't get a peek into these brands and into these resorts and into private aviation. You just, you literally had no way to have a peep hole into that world. So I don't think I knew what I was missing out on. The only thing I felt like I was missing out on was Florida.
Daniel Berk: Hmm.
Adam Katz: This amazing destination that so many of my friends seemed to go to mostly on an airplane which was a foreign, uh, vehicle to me as well. And it go-- I never went on a plane with my family and never had-
Daniel Berk: When was the first plane you took?
Adam Katz: Sixteen by myself to visit a camp friend.
Daniel Berk: Wow.
Adam Katz: And then the first time my toes went into sand, and I grew up in Rockland County in New York so the Jersey Shore wasn't that far away but-
Daniel Berk: Yeah
Adam Katz: ... my parents weren't into sand. They were into concrete pool situations.
Daniel Berk: Yeah.
Adam Katz: Um, the first time I actually had my feet in sand was when I met my wife at a vacation in Turks and Caicos, Club Med-
Daniel Berk: Oh goodness
Adam Katz: ... when I was twenty-four years old.
Daniel Berk: It's interesting to hear your story and then you ended up at Merrill Lynch, right? I mean tell me kinda how that happened 'cause that's fairly drastically different than the story you just told us so...
Adam Katz: Psychology always I thought was interesting and so my girlfriend at the time, she had a friend. So I remember being a junior in high, in, in, in college and we're sitting in my parents' house and my girlfriend's there with me and we're talking about her friend that had just gotten a job at this, at this firm Merrill Lynch which I like to tell people I felt was a residential real estate firm like Cork, and it was.
Daniel Berk: That's, yeah.
Adam Katz: I was just about ten to twenty years stale but in-
Daniel Berk: Yeah
Adam Katz: ... my mind's eye this was just like, you know, there were signs out on people's lawns that said Merrill Lynch. Um, and I didn't really know what it was and, and this guy was doing investment banking which I definitely didn't know what it was. I joke I thought banker towers sounded pretty good. You like got it at four or five so like clearly missed the joke. But he was making fifty ... thousand dollars, $50,000. My dad made $48,000 after having worked for 31 years. So I found myself cold calling the white pages, I think it was the white pages when that was a thing.
Daniel Berk: Mm-hmm.
Adam Katz: And I made my way through the financial services, made my way to Merrill Lynch, and what I've always been good at is talking. I'm good at telling stories. I'm good at contextualizing stories, saying things slightly differently than other people have. And I somehow finagled my way into an internship, ironically, with Merrill Lynch, and I commuted longer than I worked, meaning I would take the train in-
Daniel Berk: Good grief
Adam Katz: ... from where I was in Waltham, which wasn't that, uh, you know, budding of a town as it is today. I'd hop on the commuter rail back and forth. I think the commute was three hours, and I was there for two hours, and he didn't pay me-
Daniel Berk: Three one way?
Adam Katz: ... to be an advisor. Yeah.
Adam Katz: No, no, no.
Daniel Berk: Oh, goodness.
Adam Katz: An hour and a half each way.
Daniel Berk: Totally. Okay. Okay.
Adam Katz: But I only worked for two hours.
Daniel Berk: You still-
Adam Katz: So I was commuting longer, and back then, this is 1996, 1997, he didn't have to pay me.
Daniel Berk: Mm.
Adam Katz: Like, they were allowed to do free internships, but he did pay for my train pass. Um, and then I just ended up hustling throughout.
Daniel Berk: So what was enticing about that at the time, knowing that you didn't really come from a background where-
Adam Katz: Right
Daniel Berk: ... that was in the home, and then you had no real idea what you were doing at first, to, to be enticed enough to do it, what about it was enticing?
Adam Katz: It's, it's a great... I think that there was nothing more than I could make some money. If I've never-
Daniel Berk: Hmm
Adam Katz: ... even been asked it that way. I think it was as simple as, "Wow, I could make..." By the way, I only got 33,000 as my salary. I didn't get the 50-
Daniel Berk: Nice
Adam Katz: ... 'cause it wasn't investment banking. It was in-
Daniel Berk: Wow
Adam Katz: ... wealth management, and it was in, like, leadership in wealth management.
Daniel Berk: Mm-hmm.
Adam Katz: And they, like, placed you into a group. It was a group where I say that I was an explainer, not a creator, which to me is a much higher value area of most-
Daniel Berk: Yeah
Adam Katz: ... places, especially in today's world. Um, and I was just always good at explaining stuff. I just had to get my-
Daniel Berk: Yeah
Adam Katz: ... pattern recognition, my 10,000 hours, and then, you know, you couple a pretty deep voice like this that I've had forever, uh, premature titling on the system at Merrill Lynch, and, you know, I became a guy nationally that was flying around the country in my mid-20s, um-
Daniel Berk: Wow
Adam Katz: ... helping close some of the biggest opportunities at the firm as, like, a specialist. I wasn't the advisor yet.
Daniel Berk: Yeah. Okay, so let's, to your point, let's start at the finish then. Let's, let's get into this thing.
Adam Katz: Yeah. Sure.
Daniel Berk: Tell me the numbers, and I think, uh, I wanna, I wanna kinda preface this with, like, it's a bit unconventional to be a wealth manager like yourself and to be as wealthy as you are. And so I'd love you to, to kinda walk me and the listeners through your balance sheet and what-
Adam Katz: Sure
Daniel Berk: ... wealth looks like in your name.
Adam Katz: Yeah. And just like, again, I have to contextualize. So what eventually happened is I left management for very obvious reasons. At one point, I was involved in recruiting the advisors to Merrill Lynch. I was head of sales and business development of the private bank. Probably interviewed 60 of 160 teams we brought over, so I've talked to way more of me than able to, would ever want to. Joined one of the teams I recruited. Eight years later, we felt the longer we stayed at a big firm, the less relevant we'd be to a growing-
Daniel Berk: Yeah
Adam Katz: ... portion of our clients' lives.
Daniel Berk: Fair.
Adam Katz: We start our own multifamily office. Um, we had a really fortunate dynamic over a bunch of years for so many reasons, mostly focused on bringing forward a whiteboard of wishlist ideas for our clients that we didn't wanna practice on them over the next five to 10. We ended up selling that business to what is now probably arguably the largest non-bank wealth manager for ultra-high net worth, uh, clients across the world. So that's where I live now.
Daniel Berk: Okay.
Adam Katz: Um, but when we sold that business is why I was able to have wealth creation at a bit of a different level, right? Rather than just an earner. So it is unusual. I've had some people say to me, "Wait, as a wealth manager, you're as wealthy as the client, or is what..." You know-
Daniel Berk: Yeah
Adam Katz: ... that seems weird.
Adam Katz: "You must be charging them so much." I'm like, "No."
Daniel Berk: Yeah.
Adam Katz: "I had a business that I sold, and it's..." And they're like-
Daniel Berk: Yeah
Adam Katz: ... "Oh, that makes more sense." So I will say this, and you know, you, you know, we sort of were thinking about the, the way I would talk about this. So one of the ideas I talk a lot about is raising kids in a Zillow world.
Daniel Berk: Mm-hmm.
Adam Katz: So in today's world, like when I grew up, I knew nothing about how my parents helped other people, and I knew nothing about how they helped themselves, meaning consumption-
Daniel Berk: Yeah
Adam Katz: ... and then charity. Well, you don't have a choice anymore. Your kids know everything about what you spend.
Daniel Berk: It's true.
Adam Katz: But it's nu- it's a numerator absent a denominator. The denominator is the question you're asking, net worth and/or cash flow. So, um, we talked to our kids. We had this amazing South African safari adventure, uh, in December, one of our best vacations, probably about $125,000, which right now is probably our most expensive vacation, and I can break it down and as we talk about it. But at one point, I look at the kids, and I told you how old they are, 16 to 20, and we said, "How much do you think we're worth?" And my daughter said eight million, and my son said 75 million. Pretty big divide. And we, like- ... asked them how they got to the numbers.
Daniel Berk: Huge divide.
Adam Katz: Right? We asked, and especially as everyone's listening, it's just like, "That's a big difference."
Daniel Berk: Yeah.
Adam Katz: Um, and 75 is, like, a, a real number. So, uh, we heard sort of their why and how they got there, and you know, I tried to not show disappointment. My son, who guessed the 75, was like, "You seem mad. You seem mad. You're wondering why I'm asking." I'm like, "No, no, no, just try to understand how you got there."
Daniel Berk: Yeah.
Adam Katz: And then when he tried to break down the math, it didn't really work that well. So what I would say it is that my wife and I have not yet told our kids the exact number. So-
Daniel Berk: Oh, yeah
Adam Katz: ... I think what's important for this call, 'cause I understand getting closer to the real number is extremely important, is I would narrow the band from between eight and 75 to between 25 and 50.
Daniel Berk: Okay. That's fair. Um, I'm gonna, for, for my own brain, I'm gonna call it right smack down the middle at, like, 35, 36, but 25 to 50, that's-
Adam Katz: That's definitely a number that's in the middle
Daniel Berk: ... the, yeah.
Adam Katz: Ish.
Daniel Berk: That's, uh, that's fair. And so that's liquid net worth, uh, in terms of if you needed to spend that amount of money right now, could you liquidate, or is that mostly in, like, private assets? Or walk me through the numbers.
Adam Katz: Yeah, it's a great, it's a great question. So I could make that liquid within probably 12 to 16 months Um, but it's not right now. I would say that-
Daniel Berk: And so what is it then? Break that down for me.
Adam Katz: Yeah, sure. So it's probably, I'm probably about 75% illiquid-
Daniel Berk: Okay
Adam Katz: ... and then 25% liquid. Um-
Daniel Berk: Okay
Adam Katz: ... and I would say, you know, when I think about the overall allocation right now across, you know, various private equity that has high correlation to the equity markets, and I would consider it a beta or a market investment plus actually public equities, that's probably in the 60 to 65% range.
Daniel Berk: Okay.
Adam Katz: There's probably 10% in private credit. Um, I mostly have my private credit gobbling up one of my mortgages, as I'm sure a lot of people that are on this and listen to this know that if you buy a home with cash and then take the mortgage out afterwards, you can actually deduct all the interest versus the traditional, uh, $750,000 worth of a mortgage is all you can usually deduct if you characterize the mortgage as such.
Adam Katz: But if you do it the way I and most of my clients do, you buy it with cash, you take the mortgage after, and as long as you income trace it to other investments, you can deduct all of it. So a lot of my private credit, um, helps gobble that up. So that's probably about 10%.
Daniel Berk: Okay.
Adam Katz: Um, and then I probably have another 10% that is in, I would say, drawdown style vintages of private equity, probably more venture than private equity, probably vintages back from around when I sold in, in, uh, you know, in the late... Actually, no, probably I started more in 2018, 2019. Um-
Daniel Berk: Okay
Adam Katz: ... then I've got a lot of direct co-invest. I will tell you, though, I have, like, 30 K-1s across all of this-
Daniel Berk: I was gonna ask
Adam Katz: ... and it is, it is the worst.
Daniel Berk: So is that in the 65%? Is 30 K-1s in that 65% bucket or in the 10% bucket?
Adam Katz: Oh, no, no. It's across probably... I would say it's across some of my company equity and then some of the others. But of the-
Daniel Berk: Okay
Adam Katz: ... of that 75% illiquid, there's 30 K-1s.
Daniel Berk: I, I-
Adam Katz: Um, which is-
Daniel Berk: ... had a guest on who had, like, 120 K-1s, and he... I, I, I, I asked him-
Adam Katz: Well-
Daniel Berk: "Do, do you like that?" He certainly not.
Adam Katz: No, the, the-
Daniel Berk: I don't know anyone who likes having that many K-1s.
Adam Katz: Well, what happens is you get so excited and enamored with the romance of being involved with so many-
Daniel Berk: Yeah
Adam Katz: ... of these types of investments that you can't help but, but do that. And then I'm sitting on probably, I'm in that 20% cash range right now, which-
Daniel Berk: Okay
Adam Katz: ... has a lot of reasons around it. I would say for me, though, like, I care about the size of the balance sheet. I care about the composition. I've probably got, I would say, at least 70% of it is just growing. There's a chunk of it-
Daniel Berk: Okay
Adam Katz: ... that I use a lot of the payments to sort of fund lifestyle right now. I don't mind thwarting some of the growth. That doesn't bother me. Um, and then for me, though, I think on the income side, probably about a million dollars a year after taxes.
Daniel Berk: Okay.
Adam Katz: And I gobble up at least all of it every year. And, you know, happy to dive into sort of the, the breakdown there.
Daniel Berk: Yeah.
Adam Katz: But, you know, a bunch of it is around what I say is memory making, which is a combination of vacations and donations. Those are my two biggest line items to start.
Daniel Berk: Okay. No, that's, that's really helpful, I think. Um, so 20% cash, is that, like, literally, like, in a savings account cash-
Adam Katz: 3.8%
Daniel Berk: ... or is that, like-
Adam Katz: Getting paid on time right now
Daniel Berk: So it's just... Okay.
Adam Katz: I mean-
Daniel Berk: Nice
Adam Katz: ... you know, in 2021 when a lot of people I work with had big exits, yet cash was paying 30 basis points.
Daniel Berk: Yep.
Adam Katz: Um, and obviously we can have the nominal versus real return. People are like, "Adam, but inflation," which I have a whole philosophy on inflation we can dive into over this call. Um, but for me right now, the optionality of cash, I have a lot of equity exposure, um, to... If, uh, the, the only other thing I would do with that cash is to go into more private credit. And right now for a pickup of eight, you know, not even eight, probably 4 to 5% before taxes, 'cause I've already gobbled up all the interest from that mortgage, to trade, you know, many millions of dollars of cash, of-
Daniel Berk: Yeah
Adam Katz: ... accessible liquidity is, uh, not interesting to me. I have enough cash flow from other things. Um, and part of me is a little bit in my head around just, you know, geopolitics in the world and optionality-
Daniel Berk: Yeah
Adam Katz: ... of satchels of cash. Although, of course, it's not actually sitting in a safe in gold bullion.
Adam Katz: It's, it's cash-
Daniel Berk: Yeah
Adam Katz: ... in an account somewhere, so maybe it's not as portable as I think. Um, but my team continues to try to push me off of that. But right now, my wife and I are, are pretty happy with the, the, the barbell.
Daniel Berk: Okay, so two questions. I want you to pretend I'm stupid when you explain them. The, the first question is y- you mentioned gobbling up the mortgage.
Adam Katz: Yep.
Daniel Berk: I wanna understand what that means, 'cause I think, you know, half the listeners probably know exactly what you're talking about, and the other half are like, "What? And what am I doing wrong that I can-
Adam Katz: Yeah, yeah
Daniel Berk: ... maybe start to pract-" And then the second one is the private credit. I'd love for you to break down some of your reasons behind the-
Adam Katz: Totally
Daniel Berk: ... private credit line.
Adam Katz: Yeah, yeah, yeah. No, no.
Daniel Berk: And so you can start with the first and go on to the second.
Adam Katz: Sure. So, um, and again, not giving tax advice, but-
Daniel Berk: Right
Adam Katz: ... a lot of people don't realize that if you characterize a loan as an investment loan, as long as you're offsetting it with investment income, it works. So a lot of people know, "Hey, if I have a, if I have, you know, a portfolio of securities, I take out a margin loan, and then I go invest that into something that throws off taxable income, I can match and deduct the taxable interest against the taxable income." It's actually not that peculiar.
Daniel Berk: Okay.
Adam Katz: But what a lot of people don't realize is that with a mortgage, you can do the same thing. A, you wanna make sure your accountant understands it. I always say never mix and match strategies and practitioners. So you gotta make sure-
Daniel Berk: Hmm
Adam Katz: ... the person who's gonna do your taxes... And it's funny, I was, like, just signing off 'cause it's, it's 10:15 today. So I was signing off on my... That's one of the funny things is, like, I try to explain to every one of our clients, like, "You're always gonna file an extension forever, and you're also-
Daniel Berk: Never on time
Adam Katz: ... gonna pay estimates forever." So it's always funny. Like, these are some of the new things that we'll talk about.
Daniel Berk: Yeah.
Adam Katz: One also is, like, how much liability insurance starts costing when you have a fun life. Um- But going, going back to, I actually looked today, 45 is what I'm paying a year, which I'll get into the breakdown of why.
Daniel Berk: Okay.
Adam Katz: Um, but, you know, if you think about the mortgage side real quick, again, really what you're doing is you're saying, "Hey, I bought a home." Let's just use simplicity. We can just use mine. I bought my house for three and a quarter, uh, took out a $2 million mortgage at 5% for simplicity. It was maybe 5.1. And so I have $100,000 of interest. If I take some of that $2 million and go invest it in, let's say, some private credit, and this is what I would do, a million dollars generating 10% generates that $100,000. So at that point, I've gobbled up the full $100,000 that I can deduct. After that, there's no more to gobble up, and I'm just gonna pay normal taxes on it, so I have more flexibility what to do with the rest of the money.
Daniel Berk: Okay.
Adam Katz: So hopefully that explanation makes sense.
Daniel Berk: It does.
Adam Katz: As, yeah-
Daniel Berk: Yeah, appreciate that.
Adam Katz: Yeah, sure. No, I love it. I... What I tell everyone is, like, I typically start here, and people I meet are here in terms of just information, and my goal is-
Daniel Berk: Yeah
Adam Katz: ... to narrow the gap as quickly as possible, right? Usually some-
Daniel Berk: I can tell you also know what you're talking about because it's hard to dumb down complicated things, uh, unless you really deeply understand those complicated things.
Daniel Berk: And so, you know, when, when someone knows what they're talking about, I'm like, "Hey, let's, let's dumb this down for people like me so we can kind of-
Adam Katz: No, no, I love it
Daniel Berk: ... you know, understand."
Adam Katz: And, and, and I didn't mean to glaze over. The last part, and then I know we have many more interesting things to talk about-
Daniel Berk: Yeah
Adam Katz: ... but private credit, for me, what I always like, I always explain, you know, you're, you're either gonna get paid on time or over time from an investment. So if you're gonna get paid on time, meaning someone's gonna pay you, as I already alluded to, right now my cash essentially is a, a loan to the government, right? Just call it treasuries for simplicity. It's like I'm not really nervous about them having the credit worthiness to pay me back.
Daniel Berk: Mm-hmm.
Adam Katz: And therefore right now the market clearing rate is, let's call it, high 3%.
Daniel Berk: Okay.
Adam Katz: But if I'm gonna go give that money to someone else, I gotta make sure I'm gonna get my money back. Now I'm gonna demand-
Daniel Berk: Yeah
Adam Katz: ... of course, a higher interest rate than what the government's gonna give me because they're the most credit worthy, even though they're not as credit worthy as maybe they've been other times. I personally like loans, though, that have an asset behind it, not just cash flow. So I like asset-backed loans. So most of my private credit is asset backed. Again, it's very personal to me. This isn't advice. And so for instance, like I'll be in a fund that is a bridge lender for a real estate developer. So for simplicity, imagine a real estate developer needs $10 million to build a place, and you say, "Well, I'll give you $5 million." And they're like, "Okay." And you gotta come up with the other five, so 50% loan to value. But I have first lien on the property, meaning if you stop paying, I now own this $10 million property at $5 million.
Daniel Berk: Hmm.
Adam Katz: So I don't wanna foreclose on you, but if I do, even if I have to sell it at 30 cent discount at 7 million bucks, I just made 40% on the 5 million.
Daniel Berk: Yeah.
Adam Katz: Right? I made... So I don't like to be personally in loan to own investments where they might be charging a much higher rate, have a much higher loan to value, and a much-
Daniel Berk: Yeah
Adam Katz: ... higher chance of default. I like stuff that's boring and that just-
Daniel Berk: Mm-hmm
Adam Katz: ... looks like a bond and is just clipping coupons, paying me on time. So the private credit that I personally have done is typically backed by either a physical asset like real estate or a financial asset, like some type of a lock box, if you will, that has payables that maybe have two or three time coverage of my loan. So let's say my loan's a million dollars. There's $3 million sitting in a box.
Daniel Berk: Okay.
Adam Katz: And it has nothing to do. It's bankruptcy remote for maybe the rest of the stuff. So that's the kind of private credit that I tend to be in, and it's all illiquid. So there's been so much going on the last couple years of the mismatch of the liquidity of the investments-
Daniel Berk: Mm-hmm
Adam Katz: ... and the wrappers. Um, and we've seen a lot of that where there's been confusion and frustration around the liquidity. Um, I personally tend to invest, again, this isn't me as an advisor talking, I personally invest in stuff that has a good match. Like I know I can't get the money for four years, so I don't have to worry about things going on along the way. Someone else wanting-
Daniel Berk: Yeah
Adam Katz: ... their money back doesn't impact me. So that's the kind of-
Daniel Berk: Okay
Adam Katz: ... private credit I've done.
Daniel Berk: Very interesting. Um, you mentioned earlier the vacation for $125,000. How do you, how do you break down a vacation expense like that? And then tell me more about the way you're spending money.
Daniel Berk: I, I imagine-
Adam Katz: Sure
Daniel Berk: ... $125,000, you said that was the most expensive, but if vacation and philanthropy are the two largest-
Adam Katz: Right
Daniel Berk: ... line items, I, I just wanna know more. Break it down for me.
Adam Katz: No, no, for su- for sure. And, you know, this is where I'm so comfortable talking about this because everyone who knows me can look any of this up. And as odd-
Daniel Berk: Yeah
Adam Katz: ... it doesn't mean you're gonna look it up, but, like, my kids will be like, "Oh, how much was that?" I'll be like, "$32,000." Like, well, there's no reason to lie about it. Now I'll talk about-
Daniel Berk: Yeah
Adam Katz: ... the why. And a big theme that I wanna keep harping on throughout this conversation is when you have wealth, by definition people will see what you're doing, whether it's buying, whether it's donating-
Daniel Berk: Yeah
Adam Katz: ... whether it's where you live-
Daniel Berk: Yeah
Adam Katz: ... what you have on your body, the most portable forms of wealth. And it's up to you to explain your why, 'cause absent you explaining your why, people will come up with their own narrative that tends to soup them, which is interesting, right? People wanna come up with a narrative that makes them oddly sometimes feel better about themselves. So I think it's really, really important to explain your why. So for us, vacationing is just something we love doing. We love memory making. Um, of course you can memory make without spending as much money, but, you know, Dana and I love bringing the kids places. Um, we can talk about first class, 'cause that is always the proverbial, uh, uh, elephant in the room. We-
Daniel Berk: Do the kids fly first class?
Adam Katz: Yes. Yeah, we all fly first class. Um, I tell people the only people who know how you travel are the people you tell. I guess by definition I'm telling people with a big megaphone right now. But the kids never put stuff on Insta. Um, and again, we don't really-
Daniel Berk: Yeah
Adam Katz: ... take a lot of pictures. We don't share a lot. But The reason why is I'll start with one of my old partners used a really, really complicated phrase, which is a cousin to Frosted Flakes, which is they're great, and, uh, Y- Y- Yoo-hoo chocolate drink is it's great, and in this case, it's better.
Daniel Berk: Hmm.
Adam Katz: First class flying's better. Now-
Daniel Berk: It is
Adam Katz: ... we're not having a financial discussion about it yet, 'cause I need to compartmentalize this for people, but, like, it's more physical space. It's a better ratio to the bathroom if you have a mini bladder like me. You don't have to have the Greg Focker kung fu fight with the overhead bins. I think everyone would agree this is all better.
Daniel Berk: Yeah, yeah, yeah.
Adam Katz: Is it worth the money? Well, now we're gonna get into some of my frameworks, which is... Like, I'll, I'll very quickly, like, the three-digit rule is probably the most, um, sticky thing that I say. I have over 30 of these in the book. If I asked you, Dan, like, what do you know your net worth more than three digits from the left, I would tell you you probably zero chance can get more than three digits. Most people can't even get two.
Daniel Berk: Yeah.
Adam Katz: And the thing is, when you start getting into eight-figure, nine-figure wealth, you start rounding by hundreds of thousands of dollars or millions.
Daniel Berk: Hmm.
Adam Katz: And the upgrade to first class usually costs for a whole family 10, 20, 30 grand, and by definition you can't even tell me down to 30 grand what's in your account, but if you were to port it on top of your vacation budget denominator, it has massive utility. You wake up more rested. You get a little bit more sleep. You're a little better nourished, although if anyone ever served you at a restaurant what you get in first class, you'd send it back. So really we are going to get into the relative world ins- instead of the absolute world.
Adam Katz: So, so as a family, we went through, we've gone through. Things were like, at one point, Dan, it was like if it's four hours or less, they're f- they're sitting behind us.
Daniel Berk: Hmm.
Adam Katz: But I like being with my kids. It's actually-
Daniel Berk: Yeah
Adam Katz: ... as simple as that. I like being with them. They understand what it mean... When they hang out with their friends, they fly coach, although because they fly so much, they have pretty good status on their own, which is a little bit of a-
Daniel Berk: There you go
Adam Katz: ... weird unintended consequence. I guess we can stop putting their record locator in there, but- ... they're pretty-
Daniel Berk: Yeah
Adam Katz: ... they're pretty savvy at this point. So I would say for us, we probably are spending 250 to 300 on vacation a year. Um-
Daniel Berk: Okay
Adam Katz: ... we vacation-
Daniel Berk: Is that one vacation, or is that-
Adam Katz: No, no, no, no, no
Daniel Berk: ... five vacations? I mean, how many vacations are you taking?
Adam Katz: I sort of, I vacation more than anyone I know. Um, and I say that half kidding, half not, but I, I vacation a lot. So we usually are going away six to eight times a year. Um-
Daniel Berk: Okay. Where?
Adam Katz: I, I, uh-
Daniel Berk: Same place? Different places?
Adam Katz: Great question. So, you know, recently if I think about the last couple years, you know, we were just in South Africa. We were in Iceland. We did an Alaskan cruise. We did Galapagos. Um, going to Thailand in a couple of months. Go to Aruba every year. Um, Dana and I did a really cool trip during the summer when we're sort of premature empty nesters. We're almost in permanence. When it's the beginning of summer camp life, you like it. When you're getting close to permanence, you don't. But she and I, uh, went in through Lucerne down to St. Moritz. We did-
Daniel Berk: Hmm
Adam Katz: ... the Glacier Express, which was super cool, and then took another train to Lake Como back through Milan to do some shopping. We're pretty good at that sport. Um, so really, I mean-
Daniel Berk: Wow
Adam Katz: ... it's a pretty wild pin across the map.
Daniel Berk: So-
Adam Katz: Yeah
Daniel Berk: ... between your wealth management, w- your, let me, let me make sure I'm clear here, your wealth management and then also your job as a wealth manager and then these vacations, who's taking care of all this stuff?
Adam Katz: Yeah.
Daniel Berk: 'Cause that's-
Adam Katz: No, I appreciate that. I, I have-
Daniel Berk: You're certainly not the one managing all that, right?
Adam Katz: Well, it's, it's so funny. Like, if you hire the right way and empower people, you actually are the least interesting person potentially to your clients on a day-to-day basis. So what I always say is I get to know people. Um-
Daniel Berk: Hmm
Adam Katz: ... I'm gonna massively upgrade the situation if you start working with me. There's gonna be a lot more people than just me, and as-
Daniel Berk: Yeah
Adam Katz: ... you can gather, you know, I like to chat, and we do-
Daniel Berk: Yeah
Adam Katz: ... half-hour calls a lot of the times, and if I'm on the call, we're not gonna get to anything substantive. So the way I really set things up is that people hit me with the highest, best use of stuff that really only I can help with. A lot of it's around transactions. They're negotiating secondaries, negotiating terms for bankers, for IPOs, M&A, gnarly stuff around family, around kids, around donations, around aging parents. You'll get me anywhere on the planet, and in my auto signatures, I always put in my out of office where I am, and then I write-
Daniel Berk: Nice
Adam Katz: ... at the end, "If you need me, you know how to get me." I don't put my phone number there. I mean, the way I end the-
Daniel Berk: Yeah
Adam Katz: ... the way I end-
Daniel Berk: If you don't know how to get me, you must not need me.
Adam Katz: Then you're not, then you're not really with me.
Adam Katz: It's funny, like, the way I end my book is something I call the scarcity seesaw. Can I actually read this real quick? Is that cool?
Daniel Berk: Yeah, please do.
Adam Katz: All right, cool. This'll take, this'll take a minute.
Daniel Berk: And, uh, before you do, what's the title of the book?
Adam Katz: Sure. The title of the book is Making the Zeros Count.
Daniel Berk: Great.
Adam Katz: It is a field guide for decamillionaires, centimillionaires, and billionaires, but the back, and this is important, it starts with stop counting all those zeros. Just make them all matter. This book is about generosity. This book is about intentionality. This book is about parenting. It's about time. So the last, uh, carry in my book, I call these little pithy ideas carries, it's called the scare- tipping the scarcity seesaw, and I think this actually is really important. This is how I end the book, and I think it's really important for anyone listening. "There will come a time when you are the thing that is scarce, not an elusive new client or customer, not the next greatest product or service, not some massive real estate deal, not that hard-to-land investor on your cap tables. No, the opposite. You are scarce, but the trick is to be intentionally abundant everywhere you wanna be, a hobby with friends, aging parents, your kid's 4:00 PM soccer game on a Tuesday." Be there, be present, be abundant, and keep your phone on do not disturb to most of the world indefinitely.
Daniel Berk: I ask every guest on this show what their net worth is. Most of them have to think about it, and it's not because they're hiding something, it's because their money is in dozens of different places. Two brokerages, a business account, some real estate, a crypto wallet they forgot about, a syndicate, and so much more. But we know that personal finance really is not that simple. Silvia fixes that. Silvia is an AI built for one very specific and important job, managing your money. You connect your bank accounts, your brokerage, your credit cards, your crypto, you add your real estate and whatever else you own, and now it knows your entire financial picture. And you can just ask it questions in plain English like, "Should I refinance?" Or, "How do I lower my tax rate?" Or, "What's actually risky in my portfolio?" Or you can ask, "What's the smartest way to pass this to my kids?" You could ask ChatGPT those questions, but ChatGPT doesn't know what you own. It also isn't trained on personal finance. Silvia is. In accuracy tests on tax, mortgages, and credit cards, it beat ChatGPT, Claude, Gemini, and Grok. In all three categories, Silvia won. The more complicated your money is, the better Silvia gets. Their data shows people who use Silvia regularly grow their net worth faster than people who don't, and this is the case at every income level and net worth bracket. Go to silvia.com, connect your accounts, ask it the question you've been avoiding, and start understanding your personal finance more accurately than you ever have.
Adam Katz: And I would say, you know, uh, what I talk a lot about with people, and I'll try to jump into some, some meaty stuff, is that, you know, because of the, the role I've had for so long, I've been able to change so many people's lives. And I know that sounds super hokey as a wealth manager, um, but by helping people reorient their relationship to money, untethering them, as I say, from like the umbilical cord that attached them to their formative years, it's really fun to play around with things. And you know, that three-digit rule really gets people thinking, 'cause it's not about the three digits or two digits to the left. You can see it's all the digits to the right you can't. And those tend to be hundred dollar units, thousand dollar units, maybe even ten thousand dollar units. And man, when you start porting that numerator where you can't even see it in your gigantic bank account-
Daniel Berk: Mm-hmm
Adam Katz: ...
Adam Katz: into little denominators where it matters, my real, real visual is imagine like a droplet of water in a, in a, in a pool in the backyard.
Daniel Berk: Hmm.
Adam Katz: And then you're, "I can't see it." And then let's just move it into the bathtub. Still can't see it. Maybe a glass. Still can't see it. Maybe a thimble. Still can't see it. Then you get it into a baby teaspoon and you finally can.
Daniel Berk: Hmm.
Adam Katz: Imagine taking so many droplets of water you literally can't see and putting them places every day. And that's probably-
Daniel Berk: Hmm
Adam Katz: ... the most exciting and fun thing, and I already told you guys I'm obsessed with and addicted to generosity. And a lot-
Daniel Berk: Yeah
Adam Katz: ... of what people remember most is I will then tell them that the idea of random acts of daily financial kindness should become second nature to you. So I have a whole tipping construct.
Daniel Berk: Hmm.
Adam Katz: I actually was looking before we got on the chat today, like I've spent 100 grand this year at restaurants. 35,000 of it is tips. So remember-
Daniel Berk: And that's not, I mean-
Adam Katz: ... that's not 30, that's not 35%
Daniel Berk: ... tell me what the biggest tip is.
Adam Katz: Yeah, I will.
Daniel Berk: Yeah.
Adam Katz: That's not a 35% tip.
Daniel Berk: Huge.
Adam Katz: That's a 50% tip on average. So I don't tip based on, um, percentage of bill. I just did some backwards math. I tip based on day part. And the reason I do this is, I'll tell the quick story of I was at a celebratory dinner with my daughter a few years ago. And the, you know, the check comes, and we were on a four top even though it was the two of us. She was, I don't know, at the time, 12, 13 years old. Obviously she wasn't drinking. That would be weird. And I wasn't drinking too much, 'cause that would also be maybe a little weird. And so the bill came, it was maybe 250 bucks, and obviously 20% tip, $50, move on, 300 bucks total. But that didn't sit right with me, because it wasn't the waiter's fault that they got a dad and his daughter at the table instead of, you know, me and Daniel and our wives celebrating something amazing-
Daniel Berk: Mm-hmm
Adam Katz: ... where we'd blow it out, we'd eat way more food, we drink a bunch, and maybe it would be a $1,000 bill, which of course would just result in a $200 tip. So I said, "Well, why wouldn't I just tip 200 bucks?" And that's what I did that night.
Daniel Berk: Hmm.
Adam Katz: And so what I d- decided to do is... And I love, I love having systems, and again, that's why I call them carries. They're like things you could have on your person, and this is what, the way I, I organize the book. Um, so I tip based on day part. Breakfast, 25 bucks. These are all minimums. Lunch, 50. Dinner, 100. If I'm getting a coffee, 10. Any drink at a bar, $25.
Daniel Berk: Wow.
Adam Katz: I also only carry, um, 20s and 100s in my pocket. I always carry a lot of cash, because most people that you want to tip don't want a QR code. You're assuming that they have-
Daniel Berk: That's true
Adam Katz: ... the same banking system as you. We're a little tone deaf-
Daniel Berk: Yeah
Adam Katz: ... as a, as a society sometimes. So I only have 20s and 100s so that I never even have to think about what the process is. So if you take my bag at a hotel or you take my car to valet, you're getting 20 bucks at a minimum. Um, when do I give 100? When, you know, I just bought a Vispring mattress. Have you heard of these mattresses?
Daniel Berk: I have heard of them. I have not slept in them.
Adam Katz: So I have some clients that maybe, you know, have been part of the other mattress companies that are out there.
Adam Katz: Um, but my wife and I recently bought one of these ridiculous mattresses that she first slept on at a hotel in Paris, and it was $33,000, to which you might be like, "Holy shit, for a mattress." Well, first of all, let's get to my first thing I said is financial wealth is a gateway to time wealth, autonomy wealth, and health wealth.
Daniel Berk: Yeah.
Adam Katz: I mean, if we can't invest in our sleep, what are we doing? Next-
Daniel Berk: Nope
Adam Katz: ... three-digit rule. I, I'm down to 33 grand. I have no idea what I have. I, I might not even know what I have down to 330 grand, which sounds gross. But like, that's the three-digit rule, and then I'm like, man-
Daniel Berk: Yeah
Adam Katz: ... what if I port it to my sleep denominator? My sleep health-
Daniel Berk: Oh
Adam Katz: ... amazing.
Daniel Berk: Huge.
Adam Katz: And so, you know, we recently gotten that mattress and it's actually, I, I, I quite love it. Um, but again, you know, as you start thinking about some of these dynamics and you think about this idea of generosity and this idea of tipping. And when they came to deliver this mattress, there were three guys, and not only did they deliver the mattress, they brought down another mattress. They brought down another mattress I couldn't move. And so as they're leaving, and they were there only in the house for like 22 minutes, they each got a $100 bill. 'Cause anyone- That's great ... who brings something to my house give- And it goes back to, like I say, if I don't know what I have in my pocket, I don't have the right to keep it there. Hmm. Which may sound controversial to people, but if you thought about, "Man, I have a lot of cash," and I don't, I don't know, do I have $1,800 in there? Do I have $1,100? Do I have $650? If you don't know, put it somewhere that matters. Take it out of the bathtub, take it out of the pool, take it out of the glass, and put it in these little baby teaspoons where the person- Hmm ... that's getting it cares about it so much. So for me, like the tipping dynamic is amazing. So this year, as I said, I turned 50. Dana turned 50. So we did some pretty blowout extravagant stuff, which I'm happy to talk about what we did, all about memory making. But I had one part, I, I celebrated eight days of May, my birthday was in May, um- Right ... and I'm happy to talk about what I did. But one of the things was we did a dinner at like our local steakhouse, which we love. We had like 14 people, and this, uh, Dana and I go there almost every week. And w- almost no matter what the bill is, they get a $250 tip from me. So if it's 300 bucks, they get 200. So they like you. They, they see you coming, they, they, they put their tie back on. Well, so, and we're gonna talk about, we're gonna talk about the difference of service, which is okay, but I like the random act of daily financial kindness where I'll never- Yeah ... see the person again. Yeah. And I'll talk about when the formative stuff happened, but I wanna finish this to answer your tip question. Yeah, yeah, yeah. So the bill was 3,000 bucks, I gave him a $2,000 tip. Wow. Just- And why? Because- Your birthday celebration let him in, yeah ... it's just, it's just- Yeah ... I wanted to make it a round number. And then just general, um, charity. I mean, we've donated probably, I don't know, 4 or 500 grand over the last few years to so many things. We're very into hyper local stuff. Some of it you might argue, do people really need your money? I don't know. We, we like to have it where it's hyper local, it's tangible. Mm-hmm. We did something really big for our synagogue after we, uh, after I sold the company. And it's funny, like that was an example of the what-why, uh, dynamic, where we're not the most religious people. Uh, we don't go very often. And people were confused like why would the Katzes... And we pretty much did a massive internal renovation. Hmm.
Adam Katz: Not structural, but I tell everyone the reason we did it is as young families move to my area and they're looking at different synagogues, I said, "I want people to say, 'Wow, this place is ready for the next 30 years, not the last 30 years.'" And it was as simple-
Daniel Berk: Hmm ...
Adam Katz: as that. Yeah. And so, you know, explaining the why, what I didn't anticipate though is the rabbi had us come up on the holiest day of Rosh Hashanah, which is the big New Year celebration, and 1,000 people at the synagogue. And he calls us up by all of our first names, so the kids weren't super psyched about it, and he asks the whole congregation, 1,000 people, to stand up. And if I needed to turn and have a conversation about money or anything like we're talking about today, super comfortable, but man, having someone talk about you and your generosity in front of 1,000 people, different. And I wasn't as comfortable-
Daniel Berk: Yeah ...
Adam Katz: as I thought I would be. So I always say to people like, "You gotta take everything out for a spin and see how it feels. Donate differently."
Daniel Berk: Yeah.
Adam Katz: "Tip differently. Fly first class. See how you feel. Buy some stuff." I always say I don't know why people think buying material stuff makes you materialistic. Like that's a weird dynamic to me. Like there's a reason why the luxury good market exists, and it's not just for aspirational folks. We actually care about attribution, and it's not 'cause we need our name on things, but I like the idea of spectrums. And if you think about two bookends of a spectrum of inspiration and shame, I don't mind living somewhere in the middle. I know a lot of people that-
Daniel Berk: Hmm ...
Adam Katz: have started donating a lot more 'cause of things they've seen me have done, and it's 'cause they're a little embarrassed. They're like, "Geez."
Daniel Berk: Mm-hmm.
Adam Katz: 'Cause their units never change. If you think about that three-digit rule and suddenly you're like, "Wait, the grandeur I used to have of a $100 bill versus what I was worth the first time I saw one. Wait, are my $100 bills $10,000 bills now?"
Daniel Berk: Hmm.
Adam Katz: "Have I readjusted when a friend asks me to donate and they're running the New York Marathon? Do I still give 100 bucks?"
Daniel Berk: Hmm.
Adam Katz: "Maybe I should be giving 1,000 bucks." We went to this place in Mexico called Grand Velas, not a, not an advertisement, but a great all-inclusive. People call it the Four Seasons of all-inclusives. And for the two rooms for the week, it was right around Christmas and New Year's, it was $37,000. Now, all-inclusive, but that, that's a pretty big number. And I had trouble getting seats every morning. So we all know that dynamic. It's very irritating.
Daniel Berk: Mm-hmm.
Adam Katz: Right?
Daniel Berk: You- Yeah.
Adam Katz: Especially here, I'm like paying all this money, I'm like, "I still have to get up at 5:30 AM? This is terrible."
Daniel Berk: Yeah.
Adam Katz: And every day, you know, you get your bill even though it's all-inclusive, and you like put a tip or you don't. So I was like probably putting my 25 bucks. Again, this was many, many years ago. So the next year I come back and I had an epiphany, and I said, "You know what? I'm gonna give them a $250 tip every day."
Daniel Berk: Hmm.
Adam Katz: So playing around with the numbers, if you do that for six days, it's $1,500. So I said to myself, "Well, if the bill for this, the week wasn't 37,000 but it was 38,500," and that package meant I never had to get up ever and I always had the same four seats where I wanted them, and I had waiters that walked around after me in the pool. Like would I check the box for the $38,500 version or... And of course, the answer is yes.
Daniel Berk: Negligible, yeah.
Adam Katz: People mentally compartmentalize money over different denominators. The idea of tipping $250 is mind-boggling to people. But if I bundle it and put it over the $37,000 denominator, it's irrelevant.
Daniel Berk: For sure.
Adam Katz: And this is where I think people get more empowered as they get to know me and hear these ideas. And again, I've been doing this one-on-one for so long. The book is now amplifying. It's a megaphone getting to lots of people I'll never talk to.
Adam Katz: And I think at, like, my hokey level, I'm hoping it makes the world a little bit of a better place.
Daniel Berk: Every year when summer ends, you tell yourself it's finally time to start taking health seriously. But work picks up, schedules fill, and your health slips down the priority list again. Does this sound familiar? This, my friends, is why a growing number of Hampton members have been loving Daily Body Coach. It's become an inside secret within the community for getting lean, strong, and healthy without the mental load of having to think about training and nutrition. Daily Body Coach is run by a Hampton member, Anthony Monica, who's also a software founder, and you feel that pedigree come through in this experience. As a customer, you get your own team of trainers, nutritionists, and psychologists who take the time to understand how you operate, what tends to throw you off, and what your daily life actually looks like. The result is a highly personalized operating system that's guaranteed to deliver results. If you want to avoid falling off, restarting, and repeating the same old cycle, you need a system that can work long term, which means it needs to be designed around your existing habits. That's what Daily Body Coach builds for you. So if you wanna transform the way you look and feel and start taking your health seriously over the long term, you gotta try Daily Body Coach. Click the link in the description or go to dailybodycoach.com/moneywise and I'll connect you directly with Anthony.
Adam Katz: With people leaning into generosity, getting the dopamine. And now on the flip side, the problem is now when we've gone back multiple times, I am swarmed by service because I don't think I realized how much money that was to these folks. Um, and then I'd always do some version of a cash tip at the end. But I think playing around with numerators and denominators when people compartmentalize... Same thing with the flights. Like, I'm like-
Daniel Berk: Mm-hmm
Adam Katz: ... well, what if the vacation was 50,000 and your flights were only five? But what if the vacation was six? Like, I play around with it. I'm like, you're just compartmentalizing the flight cost versus the-
Daniel Berk: Yeah
Adam Katz: ... whole vacation cost.
Daniel Berk: Yeah.
Adam Katz: And I think we get trapped into numerators and denominators a lot, relative value, things like that. I buy a lot of nice stuff. I like nice stuff. I'm playing around a little bit. I wore an Apple Watch-
Daniel Berk: Yeah
Adam Katz: ... for, for 13 years. And my oldest-
Daniel Berk: Oh
Adam Katz: ... my son wrote a whole essay to a private school he went to about mechanical watch movements mocking his dad who wears an Apple Watch.
Daniel Berk: Interesting.
Adam Katz: And I just, I have reasons, uh, that I just sort of abandoned nice watches because I didn't really understand how people spend 50, 100, $200,000 on watches like 15 years ago. And it just didn't make sense to me. And then what happened was, and I'm wearing it today actually, is that I was with my son. We were looking at some schools in Boston when he was getting ready to go to college, and we ended up going into Tourneau. And, you know, I, I haven't really been in a Tourneau in a very, very long time, and I tried a couple watches on, and I tried on this Rolex. And I try it on, I'm like, "This is sorta cool. I've never seen one. It's sorta black. It's matte."
Daniel Berk: It is cool.
Adam Katz: "It's sort of my, sort of my vibe." Doesn't really look like a Rolex. I'm like, "Oh, how much is that?" The guy goes, "35,000." I said, "Okay." I hadn't bought anything yet, you know, since I had sold the company. And I said, "Well, you know, I might be interested." They're like, "Oh, you can't buy it." I'm like, "What do you mean I can't buy it?" They're like, "It's for exhibition only." And I'm like, "Wow."
Daniel Berk: Classic Rolex.
Adam Katz: So I've got a willing-
Daniel Berk: Yeah
Adam Katz: ...
Adam Katz: I've got a willingness to pay, but you don't have a willingness to sell.
Daniel Berk: Mm-hmm.
Adam Katz: And I didn't really understand that part of the luxury market. And unbeknownst to me, Dana remembered that I was interested. She went to a local mall where they have a Rolex.
Daniel Berk: Yep.
Adam Katz: And she worked on it for nine months. So I forgot about it, to be very candid, and we're sitting watching TV on a Saturday. She goes, "Remember that watch you were interested in?" I'm like, "Yeah." She's like, "It's in." I'm like, "I don't... Like, what do you mean it's in?" She's like, "Well, I know you liked it, so I've built a relationship with the woman at the mall, and she got one." And what went through my mind in a split second was, "Fuck, I don't think I want it."
Daniel Berk: Uh-oh.
Adam Katz: But then I, then I flipped around and said two things. One is, what an unbelievable labor of love where I pretty much go-
Daniel Berk: Yep
Adam Katz: ... buy whatever I want whenever I want, but I couldn't buy this, and I thought it was so special and so awesome. So we go over to the mall, I try it on, I'm like, "Oh, I love it anyway," and we bought it.
Daniel Berk: Yeah.
Adam Katz: And then since then I've bought four... three more nice watches and one very, very nice watch that my wife refers to as my house watch because there's parts of the country-
Daniel Berk: That's a very, very nice one.
Adam Katz: Uh, so it's a Vacheron, which is, you know, one of the, the holy three, if you will. Um, it's a tourbillon, so it's got the really cool spinning thing. Um, and you know, it cost over $200,000. And that was the f-
Daniel Berk: And how did you, how did you figure that out, that you wanted that one? I mean, did you just see it once and then-
Adam Katz: So it's a great question. Yeah, so I did. I was like, I was at the mall right when the Vacheron store happened to open, and sometimes you can get lucky when a boutique opens 'cause they have a little inventory. So I'm trying a few watches on, and the first ones they showed me were, like, 40 or 50 grand, which I'm like, okay. And at that point I had bought a couple in that range. And then I try on this one and it's green. It's like a green matte, like, alligator leather, and it's got the tourbillon, and it's... I'm like, "Oh, this is beautiful." I try it on and I had my daughter with me, and I'm like, "How much is this?" And they're like, at the time they were like, "191." So I did take a little bit of a breath, right? My own three-
Daniel Berk: Yeah, yeah, yeah
Adam Katz: ... digit rule. I'm like, "Okay, that's a number."
Daniel Berk: Yep.
Adam Katz: And then I said, "Well, will you sell me that one?" 'Cause in my mind I'm like, even in, you know, I live near Short Hills, so it's the Short Hills Mall. I'm like, even there, I, I don't think everyone's walking in and just willing to drop 200 grand on a watch.
Daniel Berk: Yeah.
Adam Katz: And he said, "No, it's allocated to someone else." And you fast-forward many, many months later and he had it in, and it was the first time, which I liked. I like getting uncomfortable, um, 'cause it's fun, right? You, you build your bandwidth. And I'm like, oh, this is fun.
Daniel Berk: Yep.
Adam Katz: Like, I'm pretty uncomfortable about this, but I knew it was a balance sheet shift, and that's the cheat. Can I sell it exactly what I bought it for? Maybe, maybe not. But, like, you're getting 80, 90 cents on the dollar. You're not getting 30 cents on the dollar. Um, and so, you know, I've been able to buy a bunch of watches lately. Um, you know, there's been more... Like, it's funny, I was, like, looking at the year, this year's spend and, you know, it's these blowout 50th celebrations, which was probably cumulative at least 100 grand, maybe more. I'm happy to, to sort of talk about some of those.
Adam Katz: And then on the-
Daniel Berk: Yeah, walk me through all those numbers.
Adam Katz: Yeah.
Daniel Berk: Like, what did, what, let's-
Adam Katz: All right. So, so-
Daniel Berk: Let's assume this year wasn't an outlier. What are you spending for the year? Uh, philanthropy-
Adam Katz: Oh
Daniel Berk: ... tipping-
Adam Katz: Yeah, norm-
Daniel Berk: ... generosity.
Adam Katz: Yeah, normally I think we're spending in that 250 to 300 range on vacations right now. Part of it's the flights. I mean, first class travel internationally-
Daniel Berk: And that's vacation only. But what about, I mean, I'm talking investments, mortgage-
Adam Katz: Oh, yeah, yeah
Daniel Berk: ... if you, unless you own outright everything.
Adam Katz: No, no, no. Sure. No, no, sure. So I would say on the mortgage will build up. So mortgages is about 120, 130 total. They're both interest-only mortgages.
Daniel Berk: Mm-hmm.
Adam Katz: So the bigger house, uh, in Westfield where I live, uh, is around probably 100,000, 105,000 of interest. Um, and then we have a lake house that we've had almost a decade, which I call my memory maker. By the way, I bought that lake house 100% with debt way back when. Um, I actually used a HELOC from another house I had, plus debt.
Daniel Berk: Interesting.
Adam Katz: It's pretty wild. Like I always explain, like the survivorship bias of the journey I'm on, and of course that listen to this, like this isn't very easy. And most people would not be able to handle the volatility and the risk. But, you know-
Daniel Berk: Yeah
Adam Katz: ... you, you don't, you don't get there usually without taking a risk that most-
Daniel Berk: Yeah
Adam Katz: ... normal folks wouldn't take. So on that house, though, you know, I bought a long time ago, way before COVID, and as I said, we called it the memory maker. You know, not only my kids, but so many of my friends' kids probably will talk about this lake house they went to, and they probably went like five or six times, but in their mind's eye it'll be 50 or 60 times.
Daniel Berk: Oh, yeah.
Adam Katz: And I learned to wakeboard, and I learned to, to do this and that. And like that to me, and we don't use it as much anymore. Fortunately, it's under an hour from here, so I can get back-
Daniel Berk: Cool
Adam Katz: ... and forth easily. Um, but between those two, it's about maybe 115, 130. Property tax is where I'm probably the dumbest, uh, financial advisor out there, 'cause my kids don't even go to the schools. And by the way, with SALT, can't really deduct it. Probably between both houses is 75, 80. Um, so you sort of get to-
Daniel Berk: Okay. So you're at 200 between the houses, and then you have 250 for vacations, so we're 450.
Adam Katz: Yep.
Daniel Berk: Plus let's say 100 on food, plus the $50, or you said 35,000 in tipping. Let's just say 150, so we're at like 600, right?
Adam Katz: And then probably about 150 a year in donating.
Daniel Berk: Okay.
Adam Katz: Um-
Daniel Berk: Outside of the tipping. This is just philanthropy in general.
Adam Katz: Oh, yeah, yeah.
Daniel Berk: Yeah.
Adam Katz: Full on actual charity.
Daniel Berk: Yep.
Adam Katz: Yeah. I always say like the-
Daniel Berk: Yeah
Adam Katz: ... the... And I guess my housing is closer than I thought it was when I hear that. Um, we shop a lot. I mean, it's sort of a, a thing to say. I mean, definitely-
Daniel Berk: A few thousand dollars a month or like $100,000 a month?
Adam Katz: No, no, no. I, I would say that, you know, there's years, a year like this year where there were a bunch of watches, bunch of bags, um, some other stuff. You know, it could be four or $500,000 in an aberrational year. I would say in normal-
Daniel Berk: Okay
Adam Katz: ... years could be 100 grand. Um-
Daniel Berk: Okay. So this year we're at about a million then with that.
Adam Katz: Yeah. And but then, like I was, I was talking to my insurance advisor, you know, $45,000 on liability insurance. So you think I've got the two houses.
Adam Katz: I've got, um, four cars, 'cause my son, you know, I've got... And I've got a young driver. So I've got two nice cars. Dana has a nice car. And then my s-
Daniel Berk: One of those.
Adam Katz: Sure. So I, I love cars in general, and I like things that most people don't have. So I have a super rare BMW called an Alpina B8, and I have it in the Alpina green. It's likely-
Daniel Berk: Cool
Adam Katz: ... you've never seen this car. They've, they move very-
Daniel Berk: Does it match your green watch?
Adam Katz: Cheesily, it now does. But, but, uh, but it-
Daniel Berk: I love it. No, that's sick. That's awesome. Don't let anyone tell you that's not sick. That's, that's super cool.
Adam Katz: I als- I also... But what I love about it is it just looks like a BMW. It's-
Daniel Berk: Yeah
Adam Katz: ... it's just a little different looking. It's got different badging. It's radically different. It's such a one-of-one car.
Daniel Berk: How much did that cost?
Adam Katz: Uh, 168. It's on both sides of the scale, right? It's try tipping differently, try doing this differently, try spending a little differently. 'Cause none of it'll probably derail you, 'cause almost none of what we're talking about, you, besides my mortgages, and like I got some car paint, but, like think about it. Almost everything I'm talking about is totally discretionary. I don't have to donate as much. I don't have to buy-
Daniel Berk: Yeah
Adam Katz: ... things. I don't have to vacation. So for me, I also believe in the bell curve of consumption, like 40s-
Daniel Berk: Yep
Adam Katz: ... 50s, and 60s. But man, 70s, 80s, and 90s are not guaranteed, and they're not guaranteed healthy. So the idea of like putting the foot to the gas pedal as far as you can to the ground, maybe through the ground, is sort of where I live. Um, and I think it's funny, you know, in the day job, I'm an enabling advisor. I often say, and this will go to some of the nominal versus real return of investments, like the only competition for living an amazing life, and I mean the memory making, the values, the showing your kids, showing community what you care about, is some terminal value you care about in your account when you're dead.
Daniel Berk: Mm-hmm. Mm.
Adam Katz: And I don't mean anyone that actually cares. And like when you use the starting denominator of 50 million, 80 million, 100, and you have more actuarial life ahead of you than behind you, which I sadly-
Daniel Berk: Yeah
Adam Katz: ... no longer fit in that camp, but a lot of people I work with do, I'm like, if you had, you know, 820 million when you die, or 423, or like, and again, inflation adjusted not as much as it is-
Daniel Berk: Sure
Adam Katz: ... but it's just math, right? Law of 72, things double every 12 years at 6%.
Daniel Berk: Yeah.
Adam Katz: Like this is just math. I'm like, do you care if you have 800 million or $600 million? But the $600 million version, you did all these crazy things-
Daniel Berk: Yeah
Adam Katz: ... all this giving, all this donating, all this helping people, all this memory making, but you have 200 million less. Or do you wanna forgo all of that stuff? And this is a play on obviously die with zero. But to me, like that's just a result of, not a goal of. Like-
Daniel Berk: Yeah
Adam Katz: ... I'll never die with... I just, I can't spend it. I mean, I guess I could donate it, but like there's just, you can't get through all of it.
Daniel Berk: Are you gonna give some to your kids? Do you have a legacy plan set up or some thoughts?
Adam Katz: So I have, I have a, I have a very good legacy plan, as you'd hope.
Daniel Berk: Cool.
Adam Katz: I'm, I'm, I'm pretty good at architecting, uh, very sophisticated income estate-
Daniel Berk: Yeah
Adam Katz: ... philanthropic plans.
Daniel Berk: I would, I would expect that.
Adam Katz: I did it myself, and you know, there's a lot of optionality I built in.
Adam Katz: I'll put it that way.
Daniel Berk: Yeah.
Adam Katz: Um, but yeah, I mean, you know, as we have more conversations with the kids about money, um, you know, I wanna be supportive, not overly enabling.
Daniel Berk: Mm-hmm.
Adam Katz: Dana and I lived in a roach-infested apartment where we would literally turn the lights on and watch for about three seconds them all run and hide. I don't think I need my kids to go through that.
Daniel Berk: Yeah.
Adam Katz: 'Cause I actually, I think sometimes people forget, like I understand grit, but just because your kids or friends go through what you went through doesn't mean they have the same result. Like, let's not-
Daniel Berk: Yep
Adam Katz: ... totally discount luck and some skill. So-
Daniel Berk: Yeah
Adam Katz: ... even if you put something through what you went through, doesn't mean they land where you landed, and I think that's important. So for me, you know, very much is obviously my kids are much older than a lot of people I chat with, you know, we care a lot about leaning into what you care about, where you have fun, where you think that your superpowers matter. I always explain, like you gotta figure out where your superpowers are, and then you gotta put yourself in an environment that cares.
Daniel Berk: Yeah, yeah.
Adam Katz: And I hope there's an environment that cares. And also, you don't have to have a linear career. I didn't really figure out what I wanted to do till I was 34. So I think it's a really weird, like pushing towards-
Daniel Berk: I'm 33 right now, and I, man, yeah, my, my career is anything but linear, I can tell you that.
Adam Katz: Right, and but it's weird we put the pressures on.
Daniel Berk: I wanna bring the plane in for a landing here and ask what I ask a lot of guests is, we call it a threshold number on Moneywise.
Adam Katz: Yeah.
Daniel Berk: And it's the number that you had or you reached where you stopped worrying about money. I'm curious what that number was for you in terms of net worth and total spending power. What was your threshold number?
Adam Katz: Yeah, no, it's a great question. I think for me, because, and this might be more common, is that I blew right through it in one day. You know what I mean? Meaning that-
Daniel Berk: Because of the exit event.
Adam Katz: Correct. Correct.
Daniel Berk: So what was it, and then how much was the, you know, blown through it, right?
Adam Katz: Yeah, I mean, I feel, what I've always told people as a practitioner, which will be my answer, is I think once you get to twenty twen- twenty to twenty-five million dollars, and you can start predictably making a million bucks a year off of that portfolio, um, you can start living a pretty great life. I'm not saying you're living exactly the life that I am right now, because you can hear I've ramped up certain things pretty dramatically.
Daniel Berk: Mm-hmm.
Adam Katz: Um, but I think when you get to like twenty to twenty-five million dollars, you're probably way wealthier than the wealthiest person you thought existed in your hometown. And that's the thing-
Daniel Berk: Mm-hmm
Adam Katz: ... that I try to r- Like forget two hundred and fifty million to an f... Like think about-
Daniel Berk: Yeah
Adam Katz: ... the unitization of money for all the survivors that we're seeing in the headlines. Again, going back to survivorship, it's like people don't normally make billions of dollars, right? Then, I mean, then money really becomes all 100% irrelevant. There's really nothing you can do to move the needle anymore of your first three digits.
Daniel Berk: Right.
Adam Katz: Everything's an asset. I don't know if people remember Brewster's Millions, but Brewster's Millions is the best movie to watch. And I know people have their own version of scorecards and things like that, and that's cool. Just that's not what motivates me. You start porting the numerator onto different denominators.
Adam Katz: So I think when you get to that twenty to twenty-five million dollar range, I think most people can live a pretty great life. The other thing is, anyone who gets to that range, you're not gonna not get out of bed again. This is what I remind all the entrepreneurs, is like if you're who you are, so many people will pay you a few hundred thousand dollars a year cumulative to just be an advisor or consultant. And then I remind people, they're like, "Yeah, but that's not that much." I'm like, "But if you're spending a million dollars a year, it's 30% of your spend." So it matters a lot. And think about even at 5%, how many more millions of dollars would you need in your proverbial account to make an extra three hundred grand? And then they start doing the math. They're like, "Oh, like another five or six million." I'm like, "Right." So-
Daniel Berk: Hmm
Adam Katz: ... I think when you get to twenty to twenty-five, and you have the ability to also probably play around with some additional income to really ramp up probably the stuff on the edges I'm talking. But otherwise, you know, you could probably spend, I don't know, fifty, sixty grand a month. And-
Daniel Berk: Yeah
Adam Katz: ... for most people, that's a pretty bangin'-
Daniel Berk: That's gonna be good for most people
Adam Katz: ... that's a pretty bangin' life. And I would say-
Daniel Berk: Yep
Adam Katz: ... that I probably thought that was where I wanted to go. Again, the stuff that has really changed for us is, you know, donating at a certain level, definitely doing some of the blowout 50th stuff, which again, aberrational for the year. I know we never touched on it, but I know we're coming up on time.
Daniel Berk: Awesome. Adam, this has been a great episode. I appreciate you sharing, uh, as transparently as you did. And, uh, I love, I love when an episode turns philanthropic. I mean, I'm a big, you know, I'm a big believer in being a generous donor as well. And, uh, I try to give whenever I can. The, the three-digit rule, I think, is, is gonna kinda reshape the way I think about even being generous and a lot, actually. I- it's, you got my gears spinning. So I, I really appreciate you sharing with us today and, and coming on Moneywise.
Adam Katz: My pleasure. And again, the name of the book, 'cause I definitely would love people to check it out, is Making The Zeros Count, and .com is the website. I'm donating 100%-
Daniel Berk: Cool
Adam Katz: ... of any of the profit to charity, which won't surprise you from this conversation or from reading the book.
Daniel Berk: Awesome. Adam's story is pretty cool. At the beginning, he talks about the house that he grew up in. When his dad sold it, there was six hundred and fifty thousand dollars on the sign and only fifty thousand dollars of equity left. His parents had borrowed against it for years to pay for college, bar mitzvahs, weddings. His dad worked thirty-one years and made forty-eight thousand dollars, and he died with a hundred and thirty-three thousand dollars to his name. Adam was sixteen the first time he even got on a plane, and he was twenty-four the first time he put his feet in sand. Now he's worth as much as thirty-five million dollars. He spends about a million dollars a year, close to three hundred thousand on vacations, a hundred and fifty thousand on donations, thirty-five thousand just in additional tips. And when he talks about any of it, he talks about the tips the most. What's pretty cool about Adam is he really does value generosity, outsized generosity, generosity that might not ever even get noticed. And that, I think, is the part that Adam would want you to take with you. The generosity doesn't show up with the money. It was there first. He was always someone who wanted to be generous and was generous with what little he had. Now, the money just made the numbers of generosity even bigger. A lot of you listening might not have twenty-five million dollars yet. I don't. I'm thirty-three.
Daniel Berk: I've got a third kid on the way, and I'm always optimizing to make sure my family has what they need. But the three-digit rule doesn't care what your number is. Everybody has digits they can't see. At my scale, it could be twenty bucks, a hundred bucks. I mean, it's definitely not a hundred thousand dollars yet. But the digits that you can't see, those are the types of monies that you have to freely give and put somewhere that might matter more. Adam's parents died before they saw any of what Adam created. He told me he wasn't as sad as he thought he'd be, and it took him years to understand why. I think that's why he's in such a hurry. He doesn't trust that his seventies and eighties are guaranteed, so he's spending what he has now, mostly on other people, because that's what gives him life. Look, Adam might be on one side of the spectrum where you're just tipping like crazy. But I know personally I'm gonna tip differently this week. People like Adam are who I get to talk to inside of Hampton, a private network for founders and CEOs doing on average twenty-five million dollars a year in revenue. If you've done three million in revenue or have had a ten million dollar exit, you gotta check out joinhampton.com. That's where a lot of these conversations start and a lot of these challenges like, "Hey, how much are you tipping, or should you be tipping more with what money you have?" Those are the types of conversations that happen behind closed doors in Hampton, and you're missing out if you're not there already. Adam Katz was a great guest, and I'm really thankful that he came on the show to talk about generosity, wealth, and life. I'm Daniel Berk. This is Moneywise. I'll see you next week.

Personally, I find being the CEO of a startup to be downright exhilarating. But, as I'm sure you well know, it can also be a bit lonely and stressful at times, too.
Because, let's be honest, if you're the kind of person with the guts to actually launch and run a startup, then you can bet everyone will always be asking you a thousand questions, expecting you to have all the right answers -- all the time.
And that's okay! Navigating this kind of pressure is the job.
But what about all the difficult questions that you have as you reach each new level of growth and success? For tax questions, you have an accountant. For legal, your attorney. And for tech. your dev team.
This is where Hampton comes in.
Hampton's a private and highly vetted network for high-growth founders and CEOs.